Tag

specialty finance

7 insights

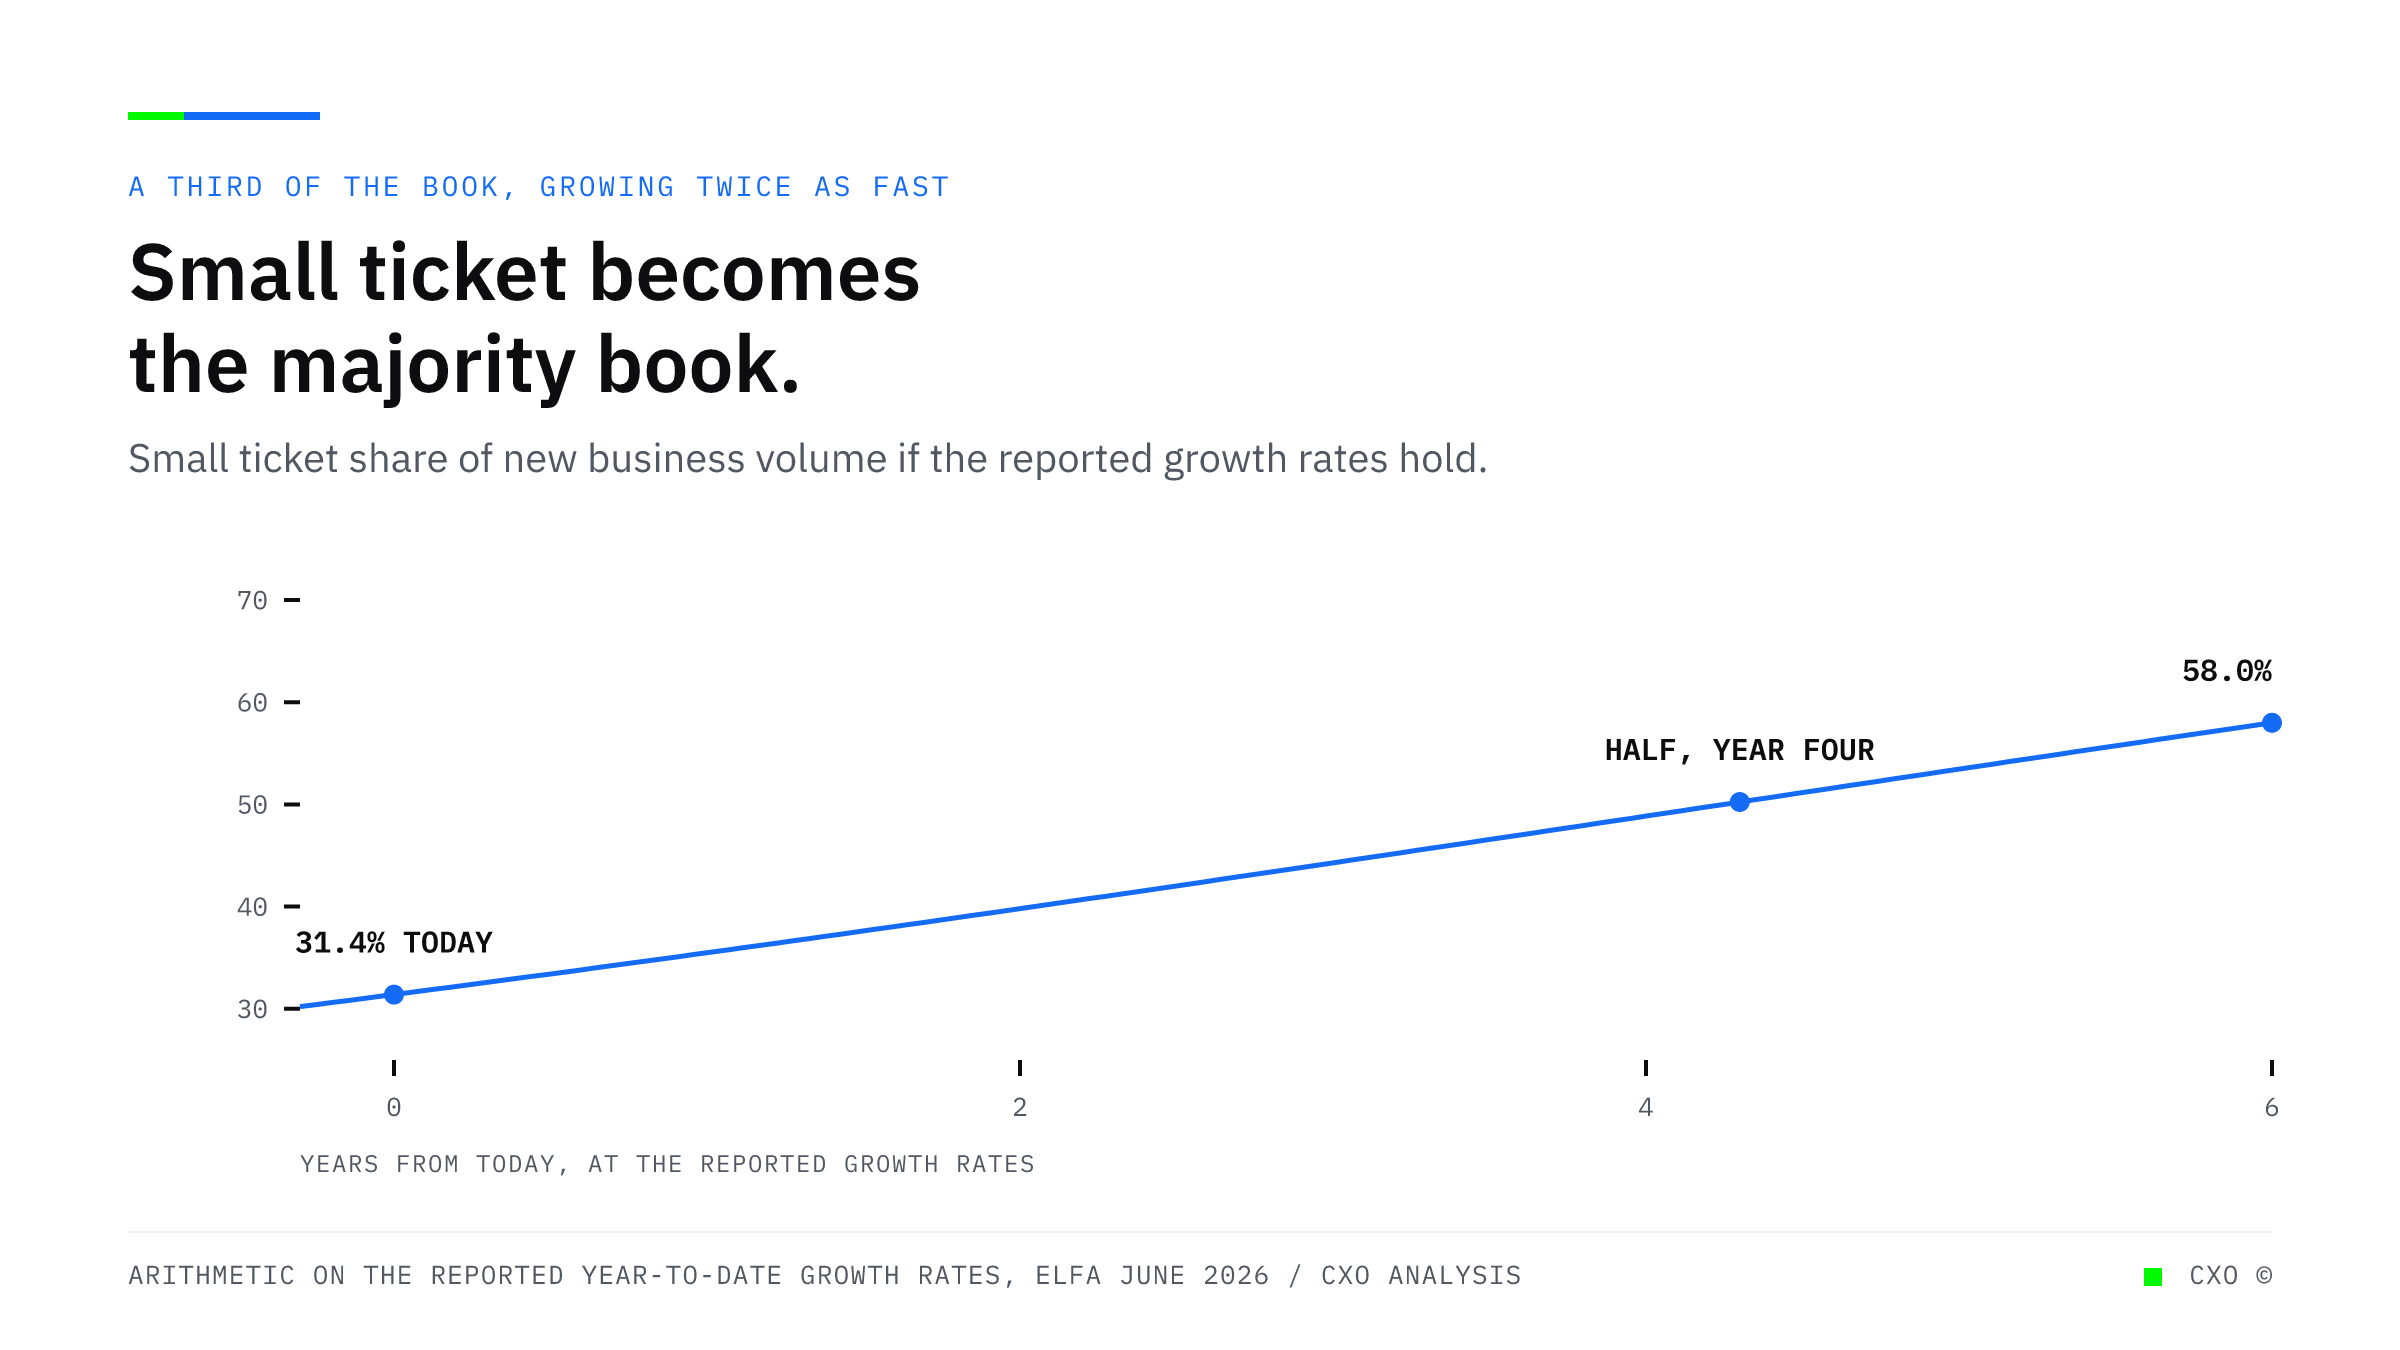
A rising curve showing the small ticket share of new business volume, starting at 31.4 percent today and reaching 50 percent in about four years and 58 percent in six, holding the reported year-to-date growth rates of 25.8 percent for small ticket and 11.3 percent overall.

Equipment Finance Is Growing Fastest in the Segment Where Margin Is Set by Cost Per Deal

Small ticket new business volume is up 25.8 percent year to date against 11.3 percent for the industry overall. The segment growing fastest is the one whose economics are decided by processing cost and cycle time rather than by credit spread.
View Insight
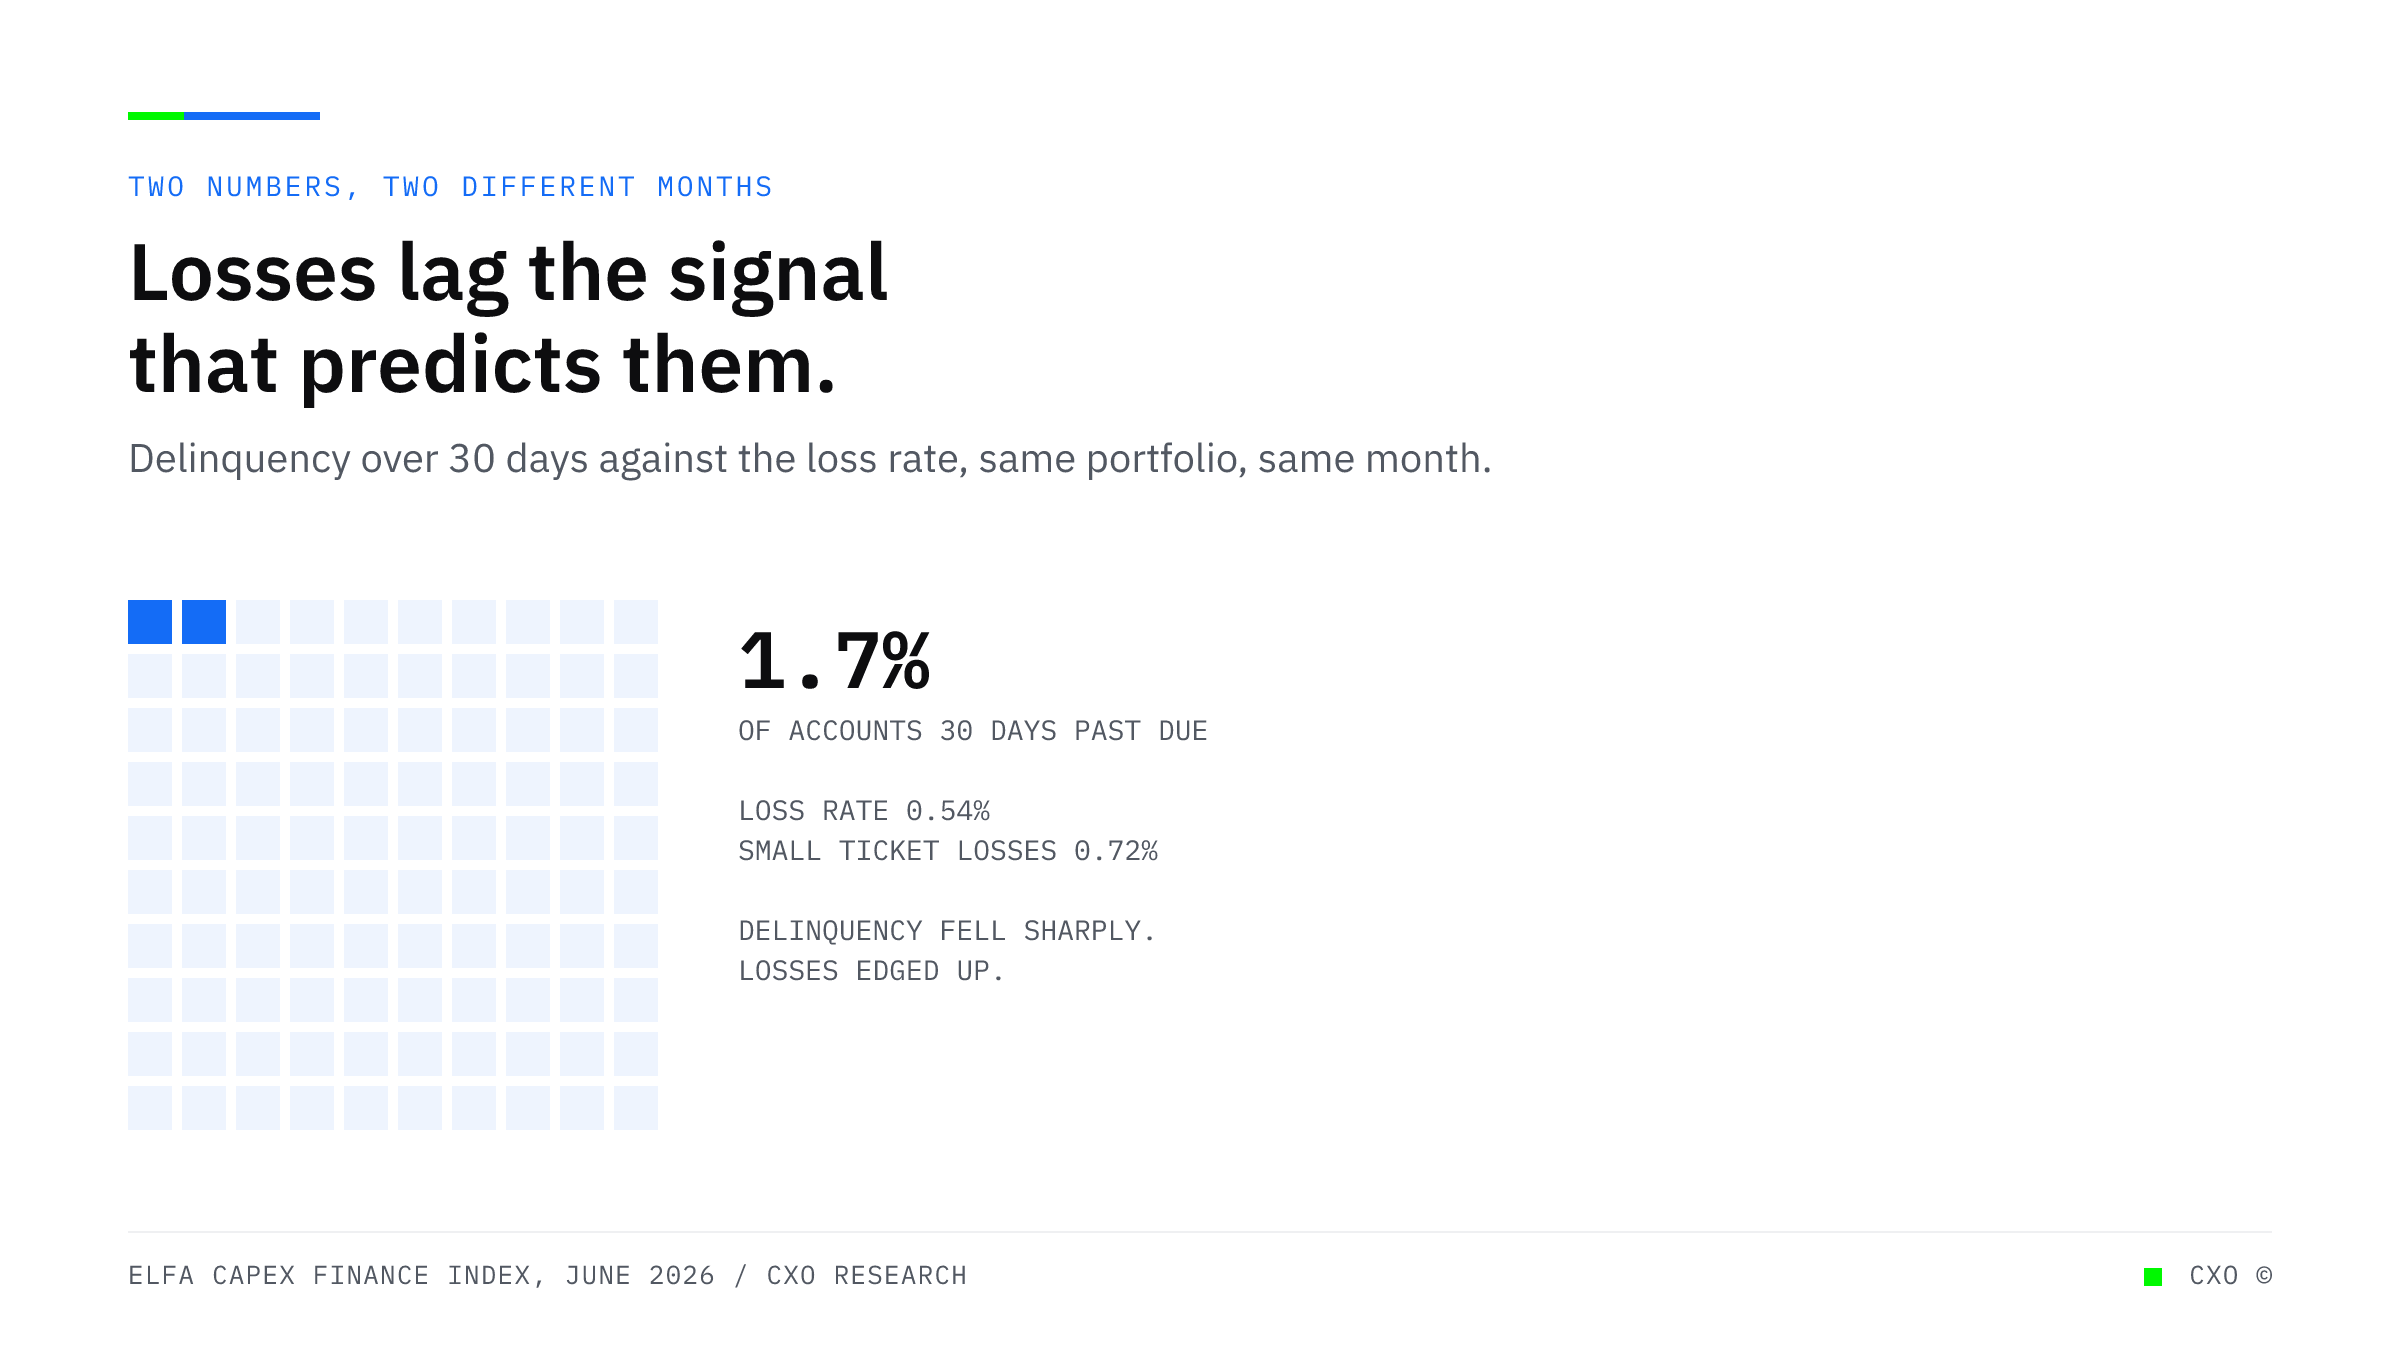
A waffle grid of 100 accounts with two marked, showing a 30-day-plus delinquency rate of 1.7 percent against a loss rate of 0.54 percent and small ticket losses of 0.72 percent.

Delinquencies Fell Sharply and Losses Edged Up in the Same Month. Both Are True.

Equipment finance delinquencies over 30 days sat at 1.7 percent in June while the loss rate rose to 0.54 percent. Losses lag the delinquency that produces them, which makes monitoring cadence a credit control rather than a reporting task.
View Insight
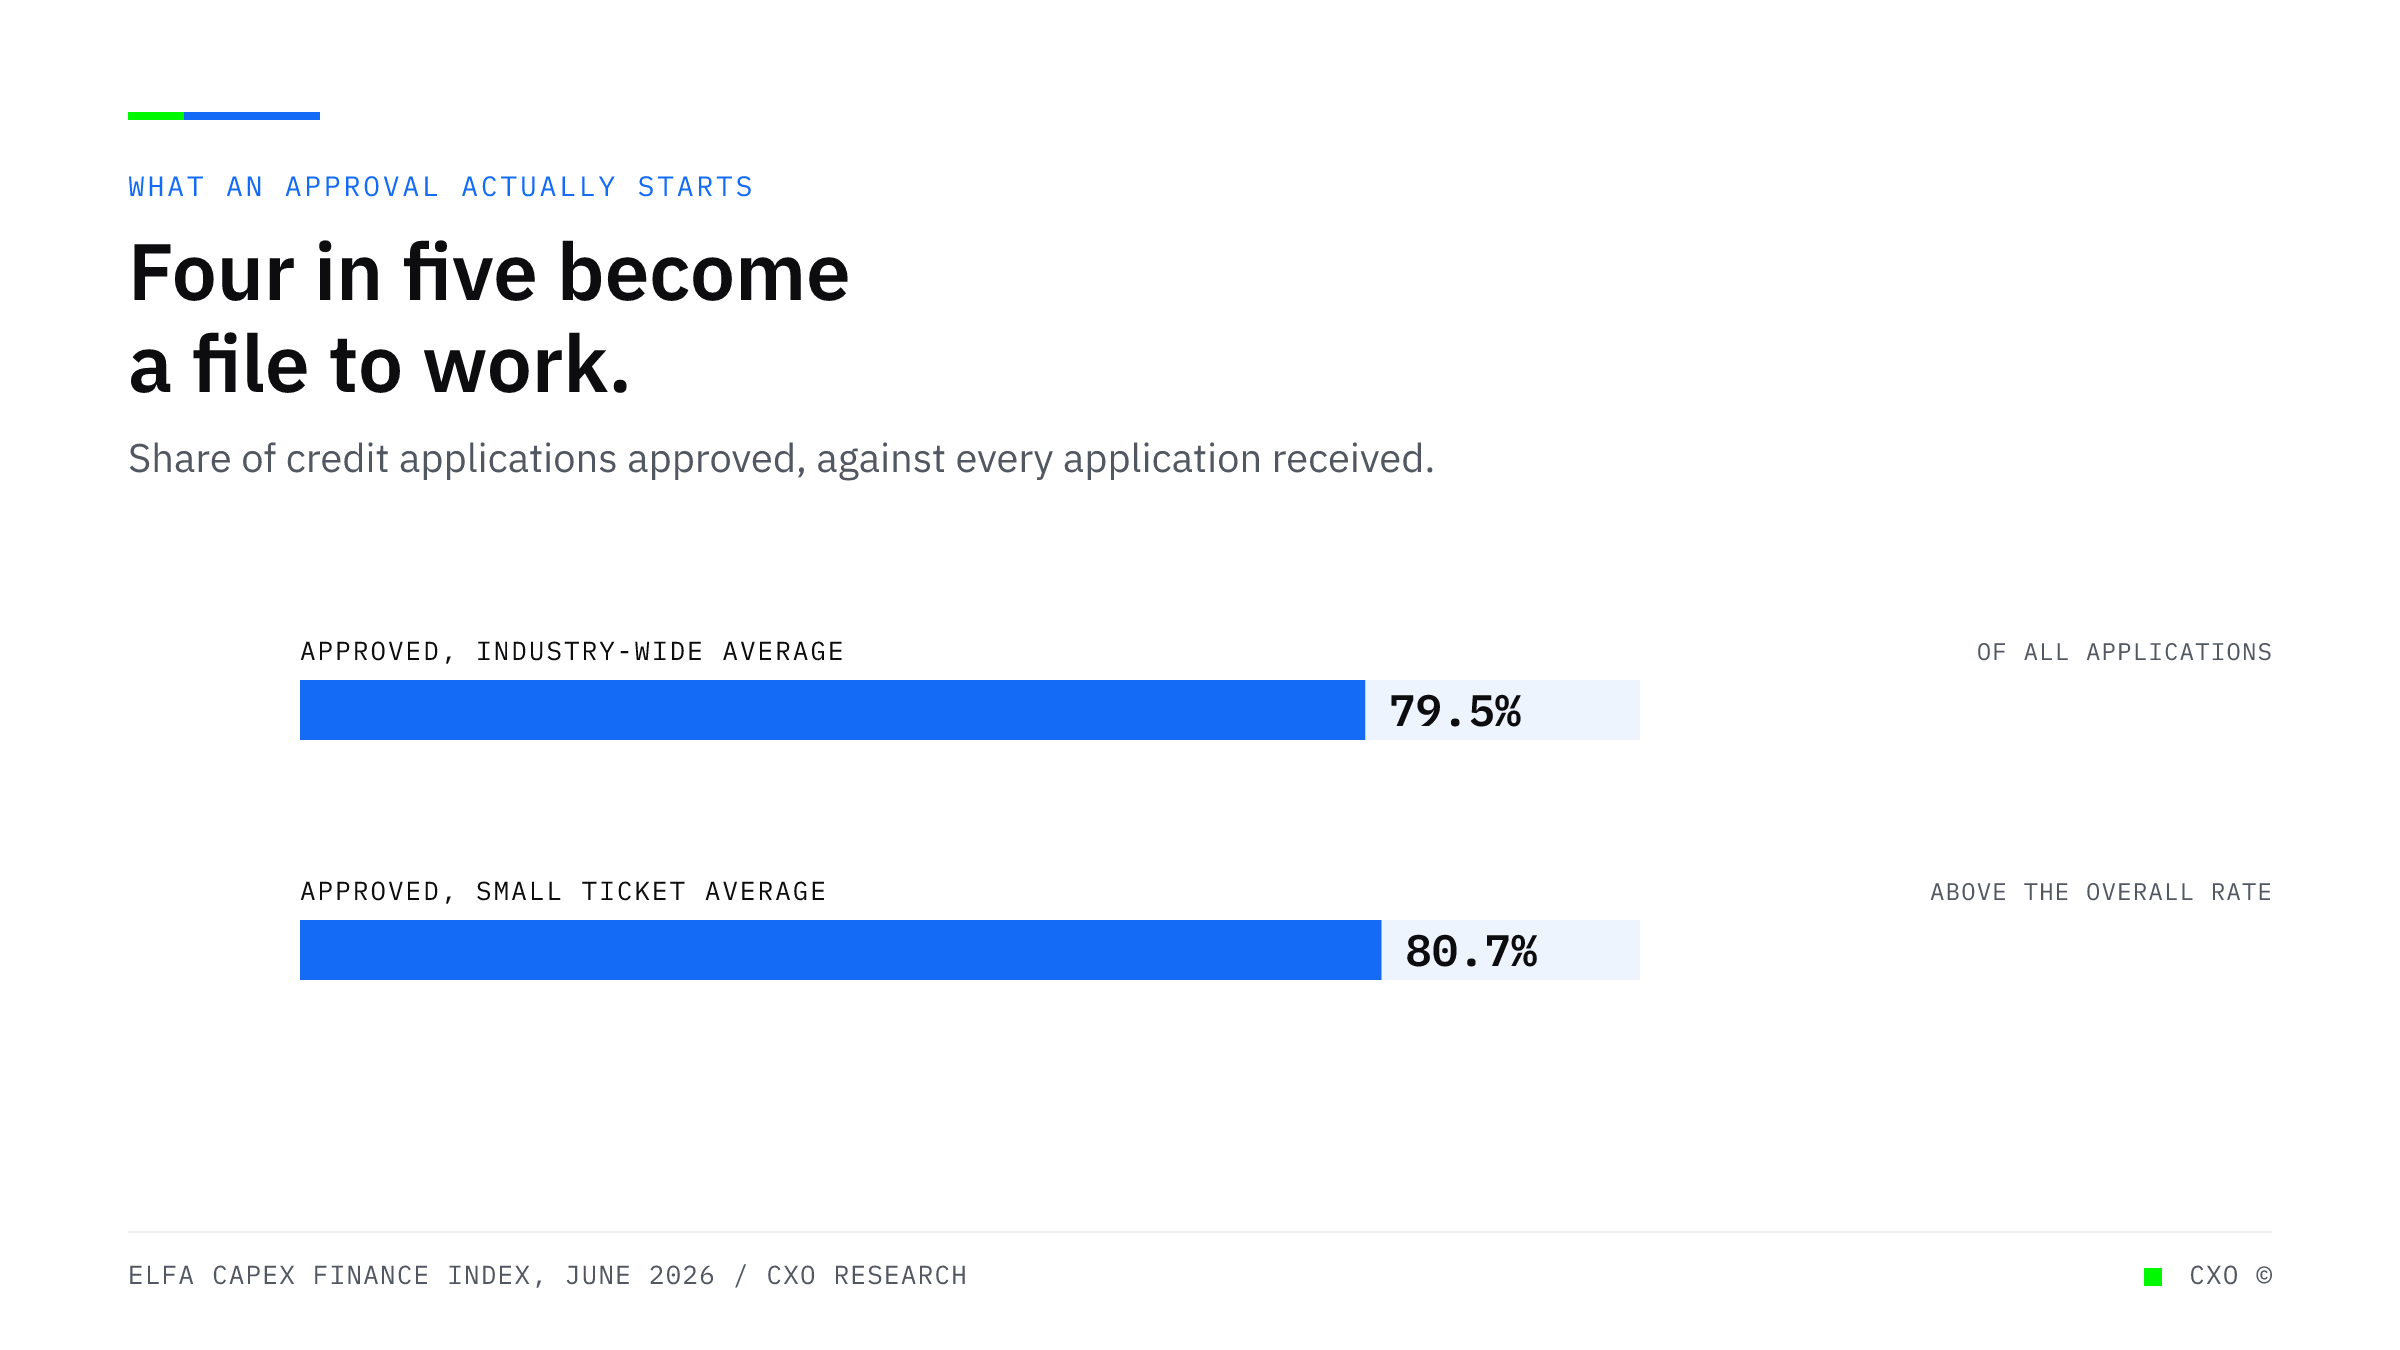
Bullet bars showing an overall credit approval rate of 79.5 percent and a small ticket approval rate of 80.7 percent, each against the full population of applications received.

Approval Rates Near 80 Percent Mean Four in Five Applications Become Work. Volume Is at a Record.

Equipment finance approval rates reached 79.5 percent in June, and 80.7 percent on small ticket. With 2026 volume forecast at the highest level since the survey began in 2006, the constraint is cost per file, not credit appetite.
View Insight
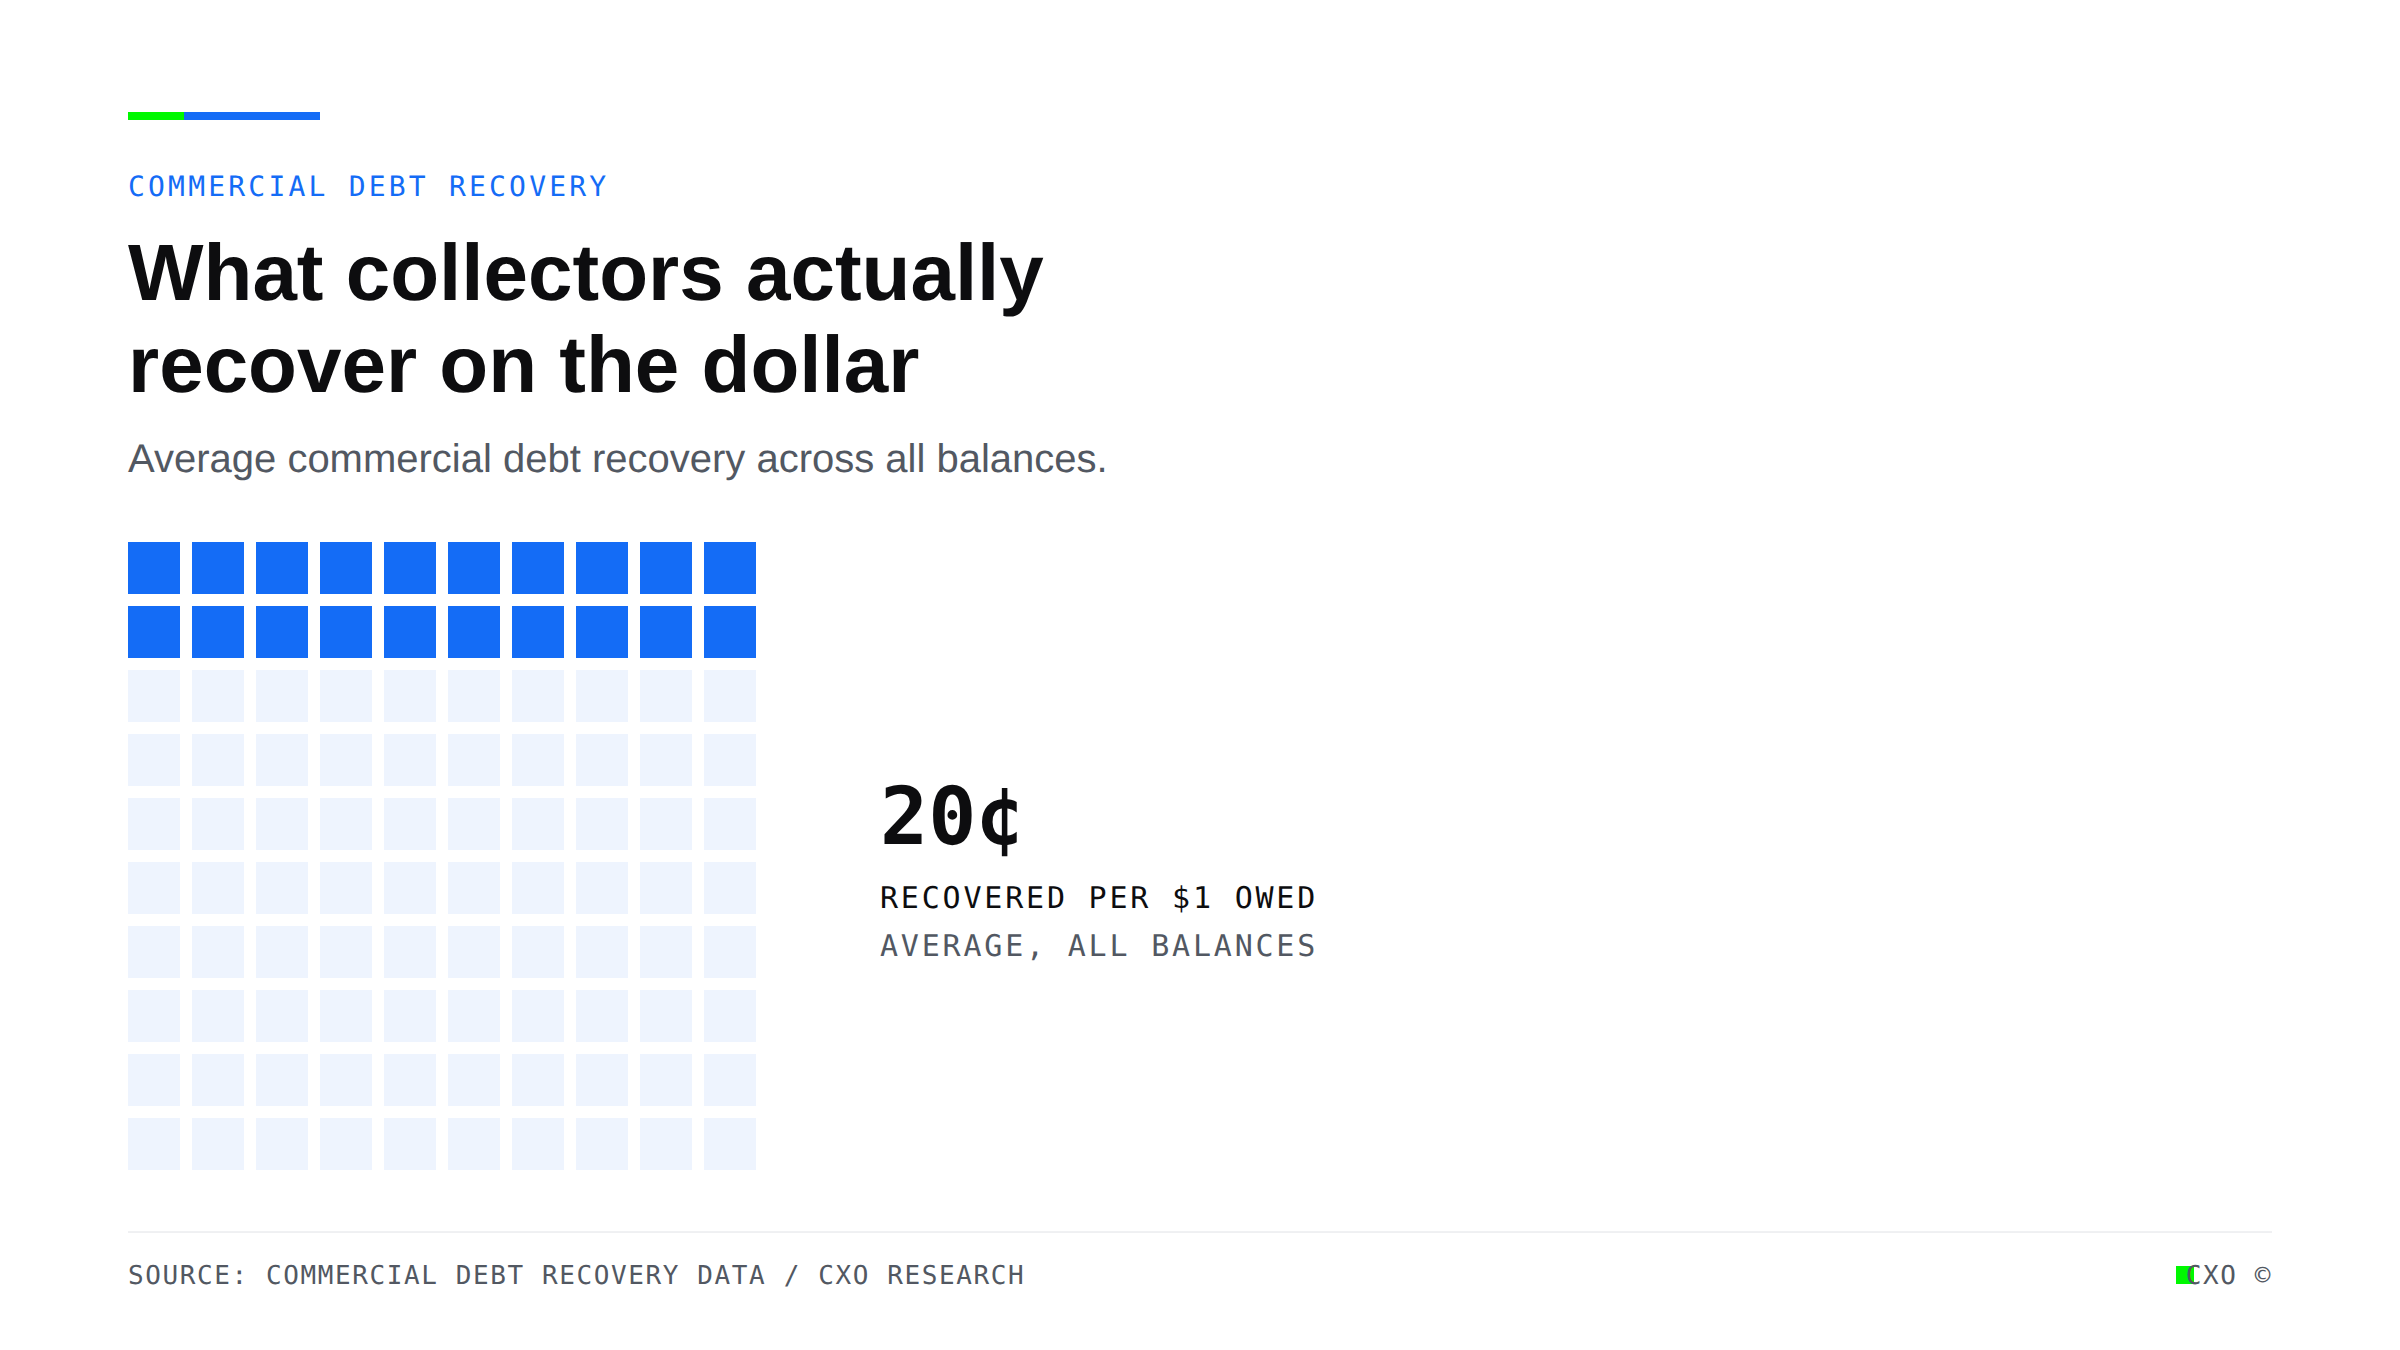
A grid of 100 squares with 20 filled in blue, showing that commercial debt collectors recover about twenty cents on the dollar owed.

Every MCA Collections Contact Is Now a Compliance Record

Federal small-business lending data rules and roughly ten state disclosure laws have turned documented, consistent MCA collections into a compliance requirement, not just a recovery tactic.
View Insight
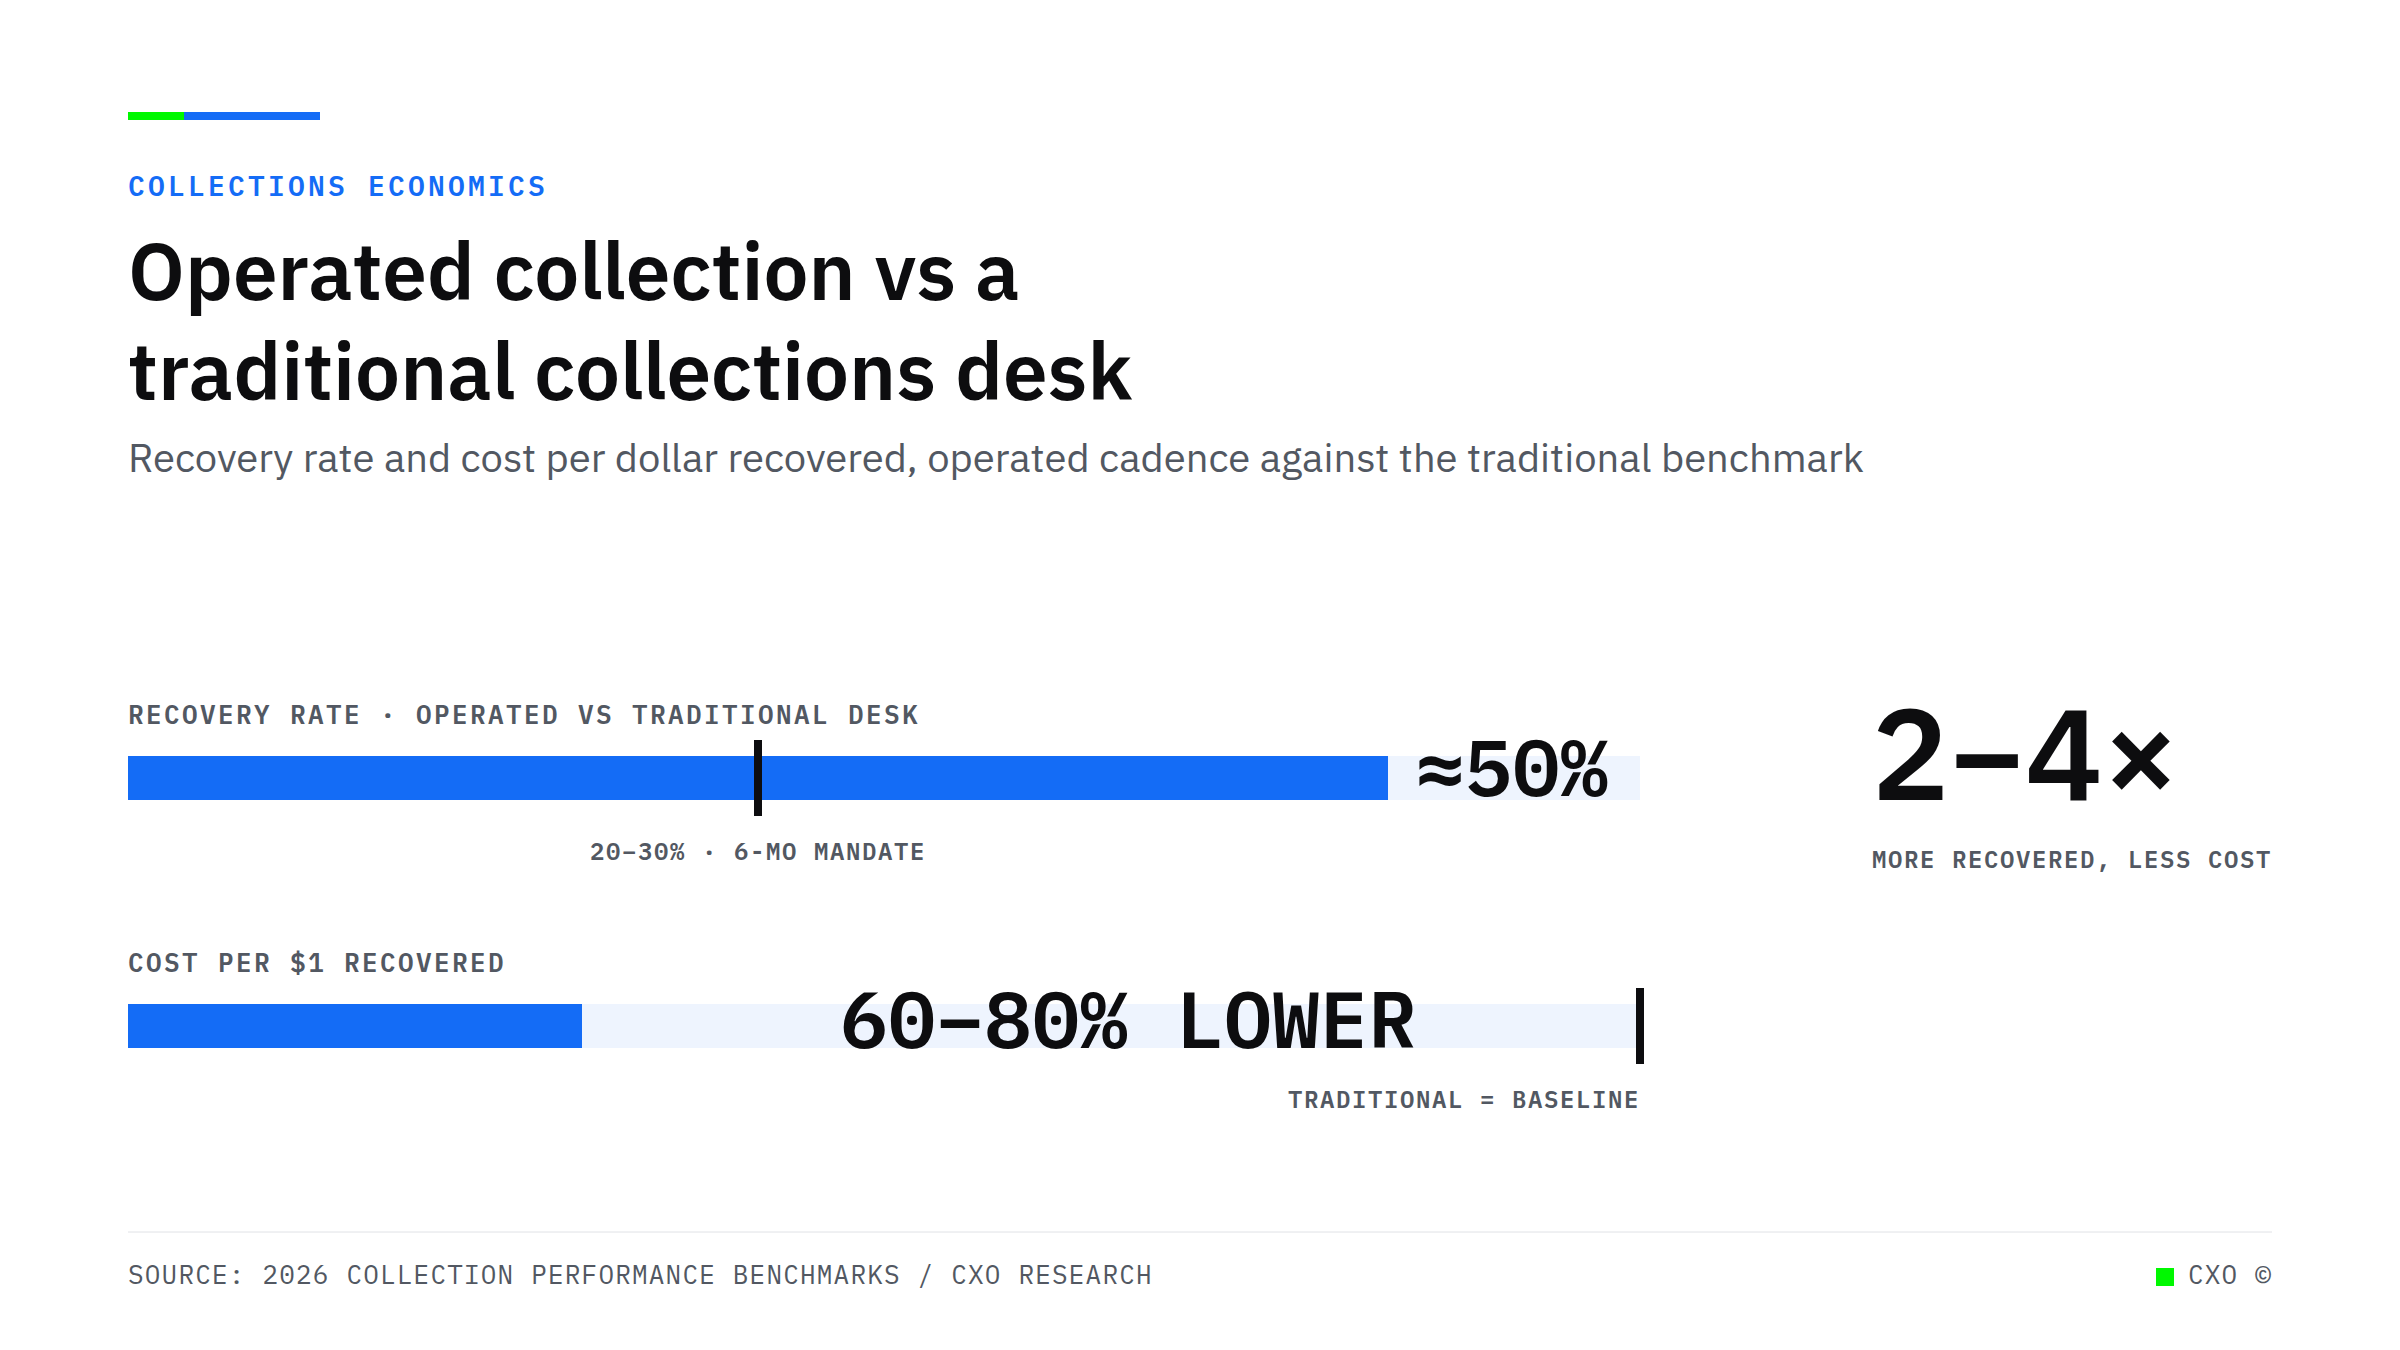
Bullet-chart cover comparing operated collection to a traditional desk: operated recovers about 50% against a 20 to 30% traditional benchmark, at 60 to 80% lower cost per dollar recovered, roughly 2 to 4 times the recovery.

The Collections Desk That Scaled With the Book Was the Wrong One

Two lenders, one book size, two collections cost structures. Why a manual desk scales with headcount while an operated cadence holds cost flat as the book grows.
View Insight
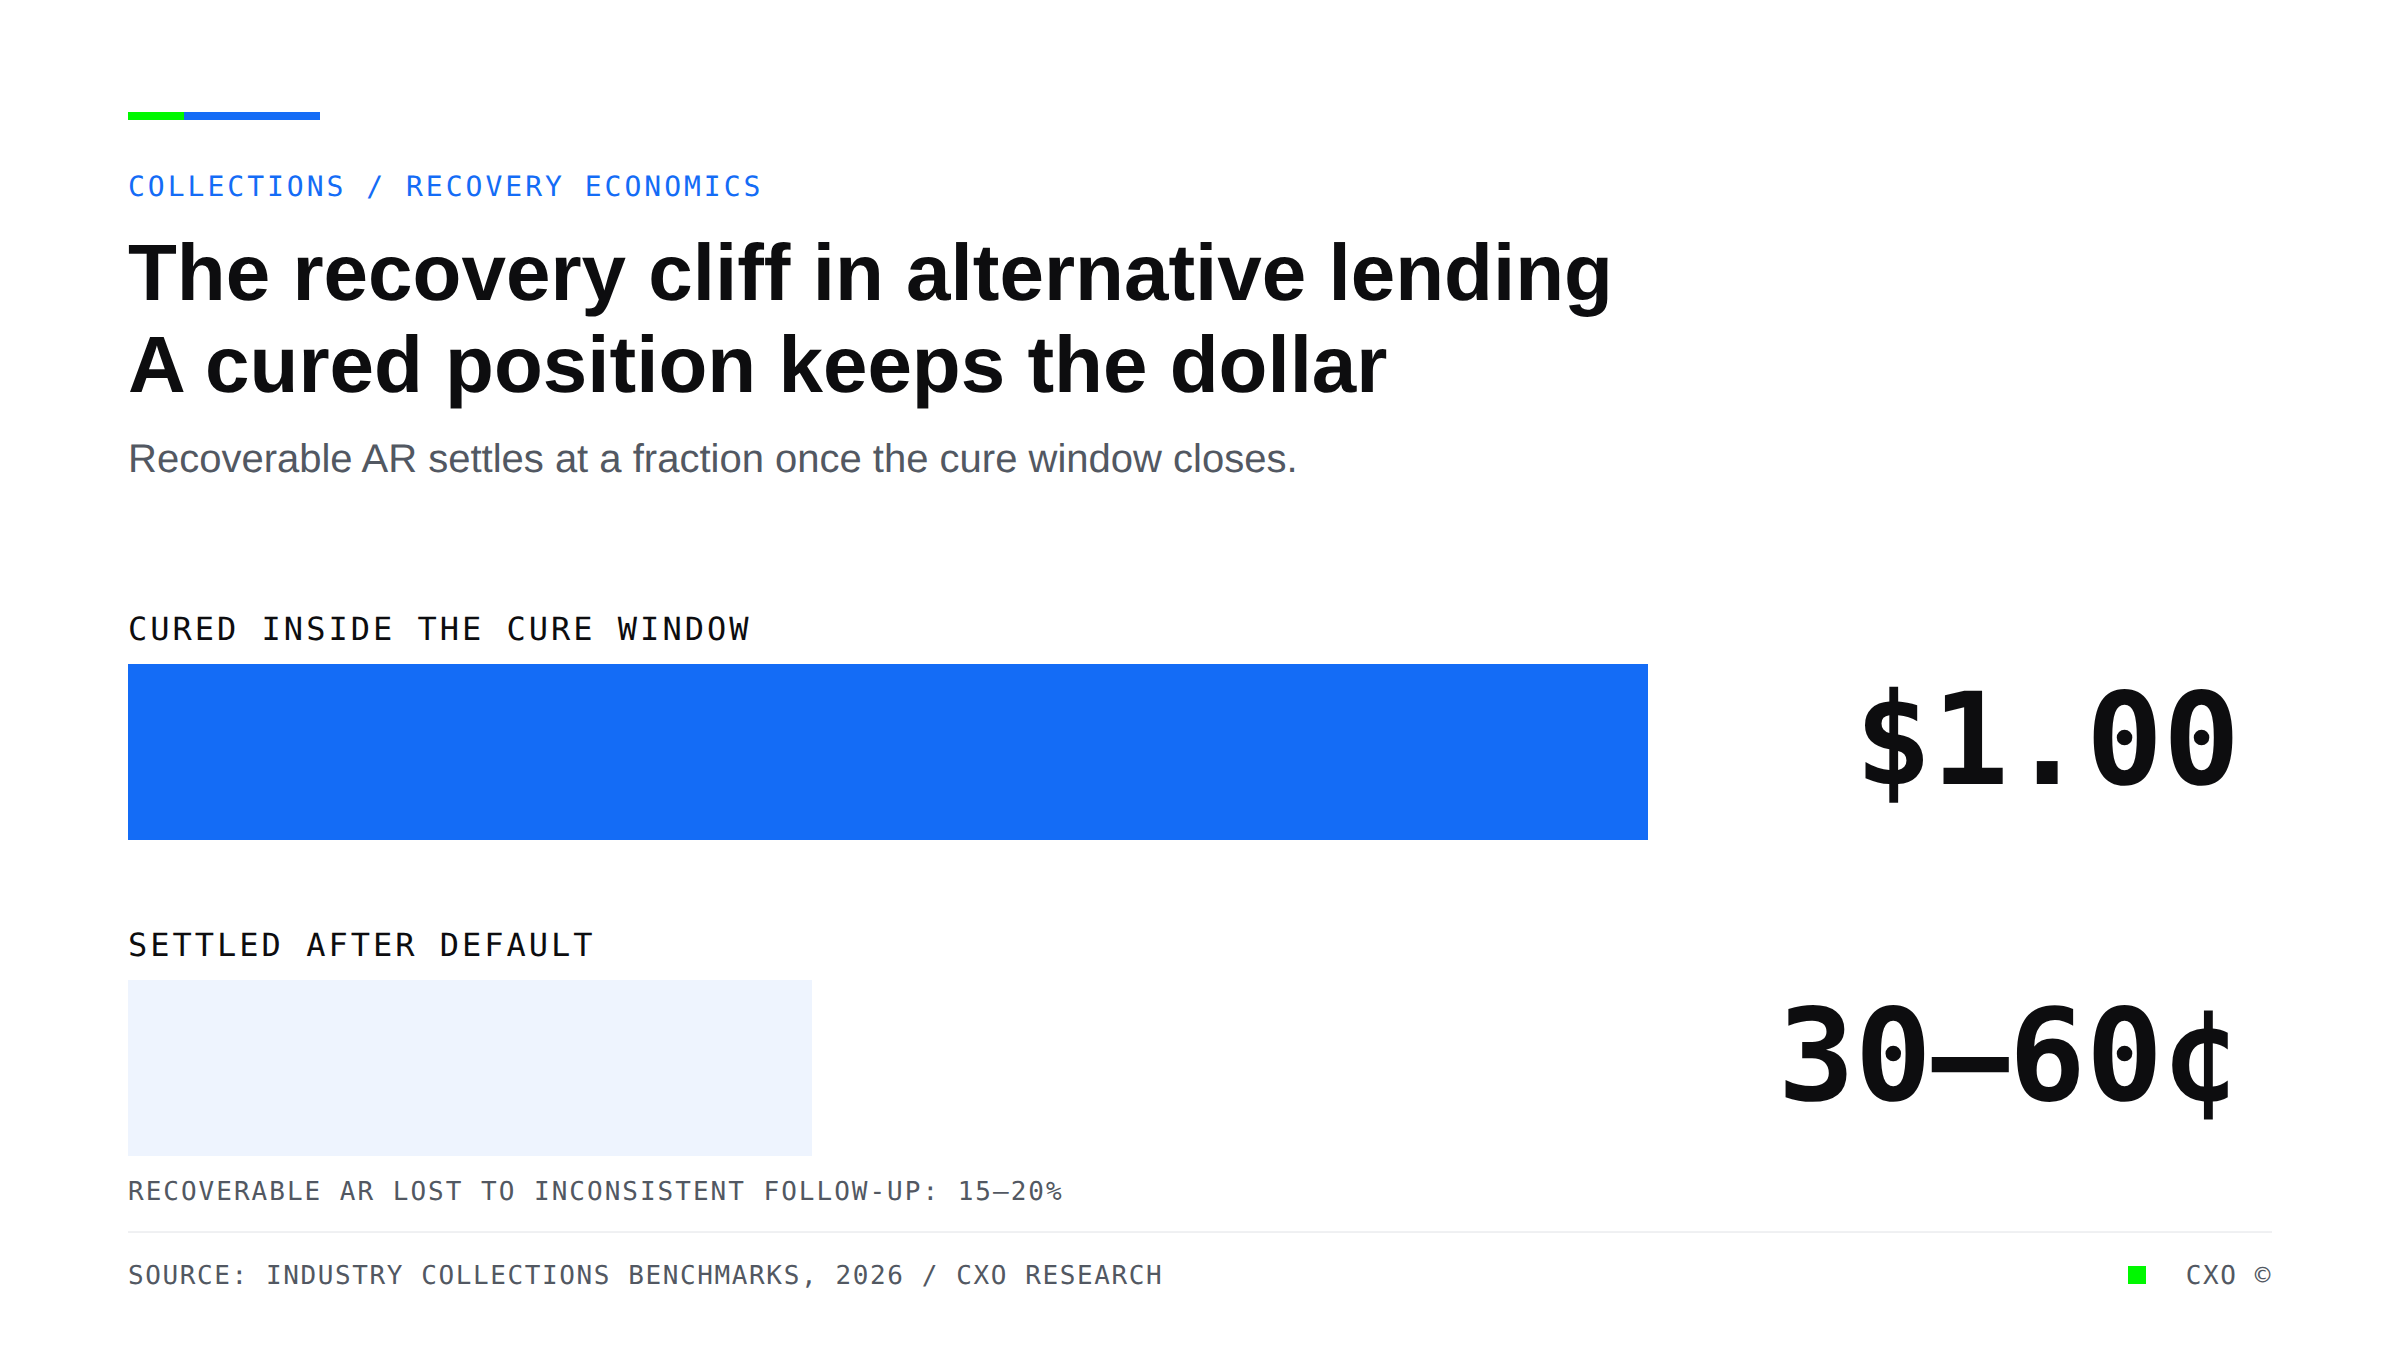
Bar comparison showing a cured alternative-lending position recovering 100 cents on the dollar versus 30 to 60 cents once it settles after default.

Your Worst Recoveries Are a Scheduling Problem, Not a Credit Problem

Alternative lenders lose 15 to 20% of recoverable AR to inconsistent follow-up, not bad credit. Why recovery is a timing problem, and how CXO closes the gap.
View Insight
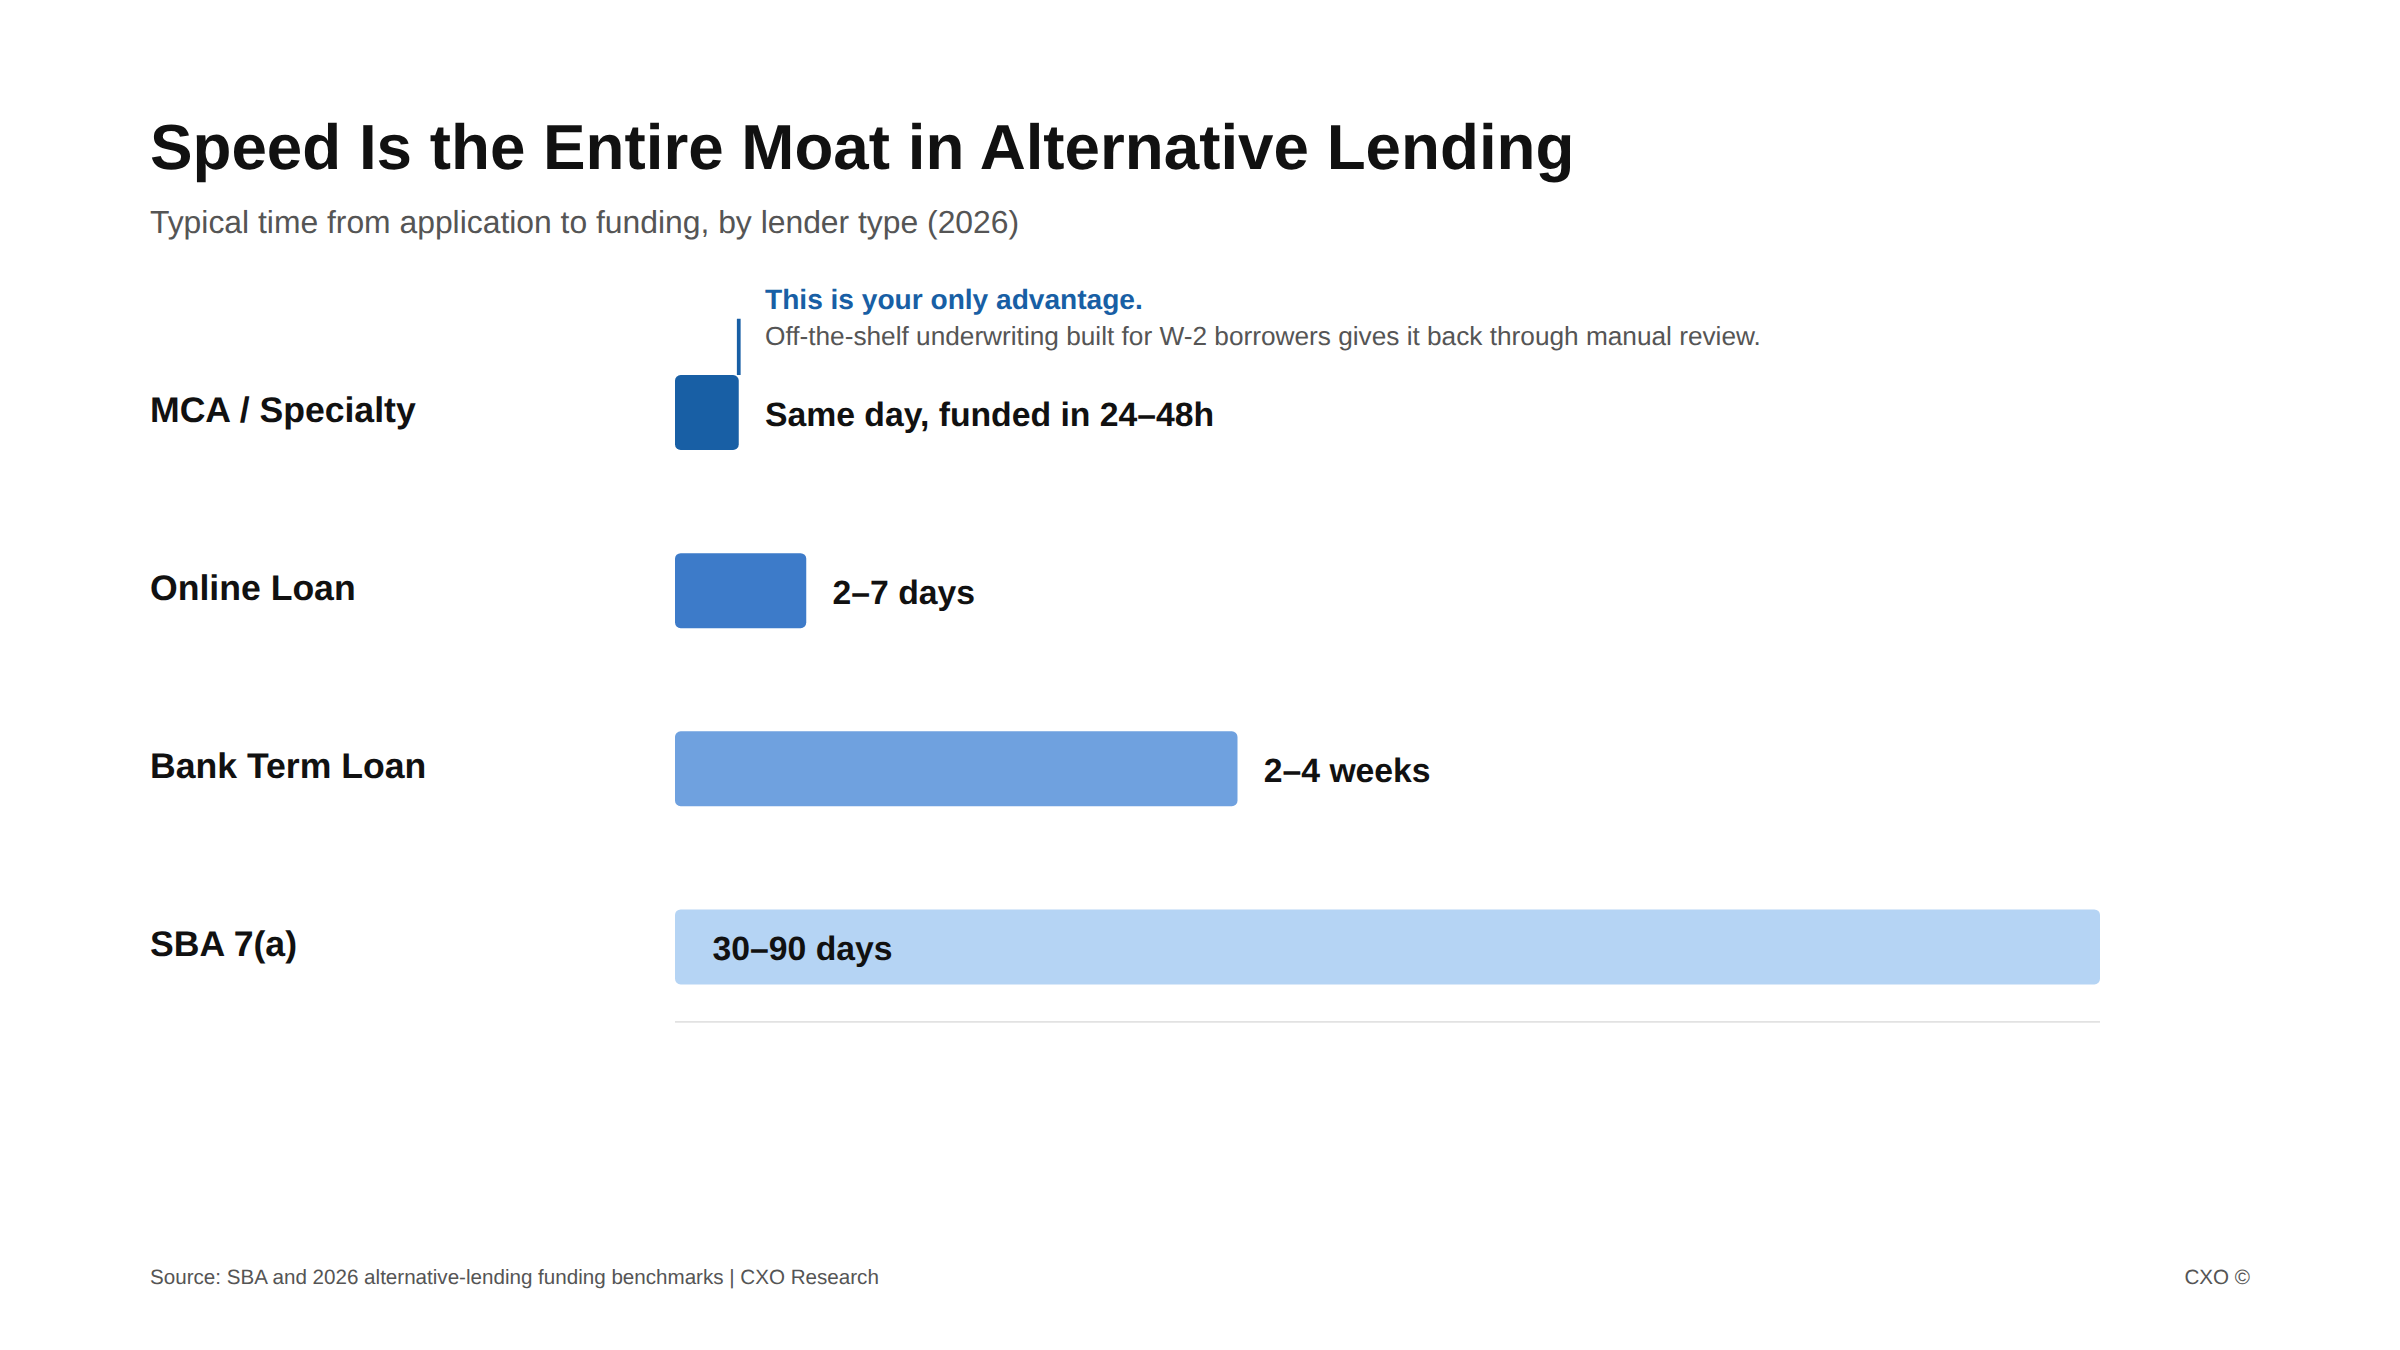
Horizontal bar chart comparing time to funding by lender type, showing MCA same-day funding against bank and SBA timelines of weeks to months

Off-the-Shelf Underwriting Was Built for W-2 Borrowers. You Don't Lend to Them.

Off-the-shelf underwriting was built for W-2 borrowers, not the cash-flow businesses alternative lenders fund. Here is where it leaks deals and how to fix it.
View Insight

Start with the process that costs you most.

A conversation first. A structured assessment when it earns one. Or see what a discovery finds before you book anything.

Book a discovery call See what a discovery finds