Tag

workflow automation

9 insights

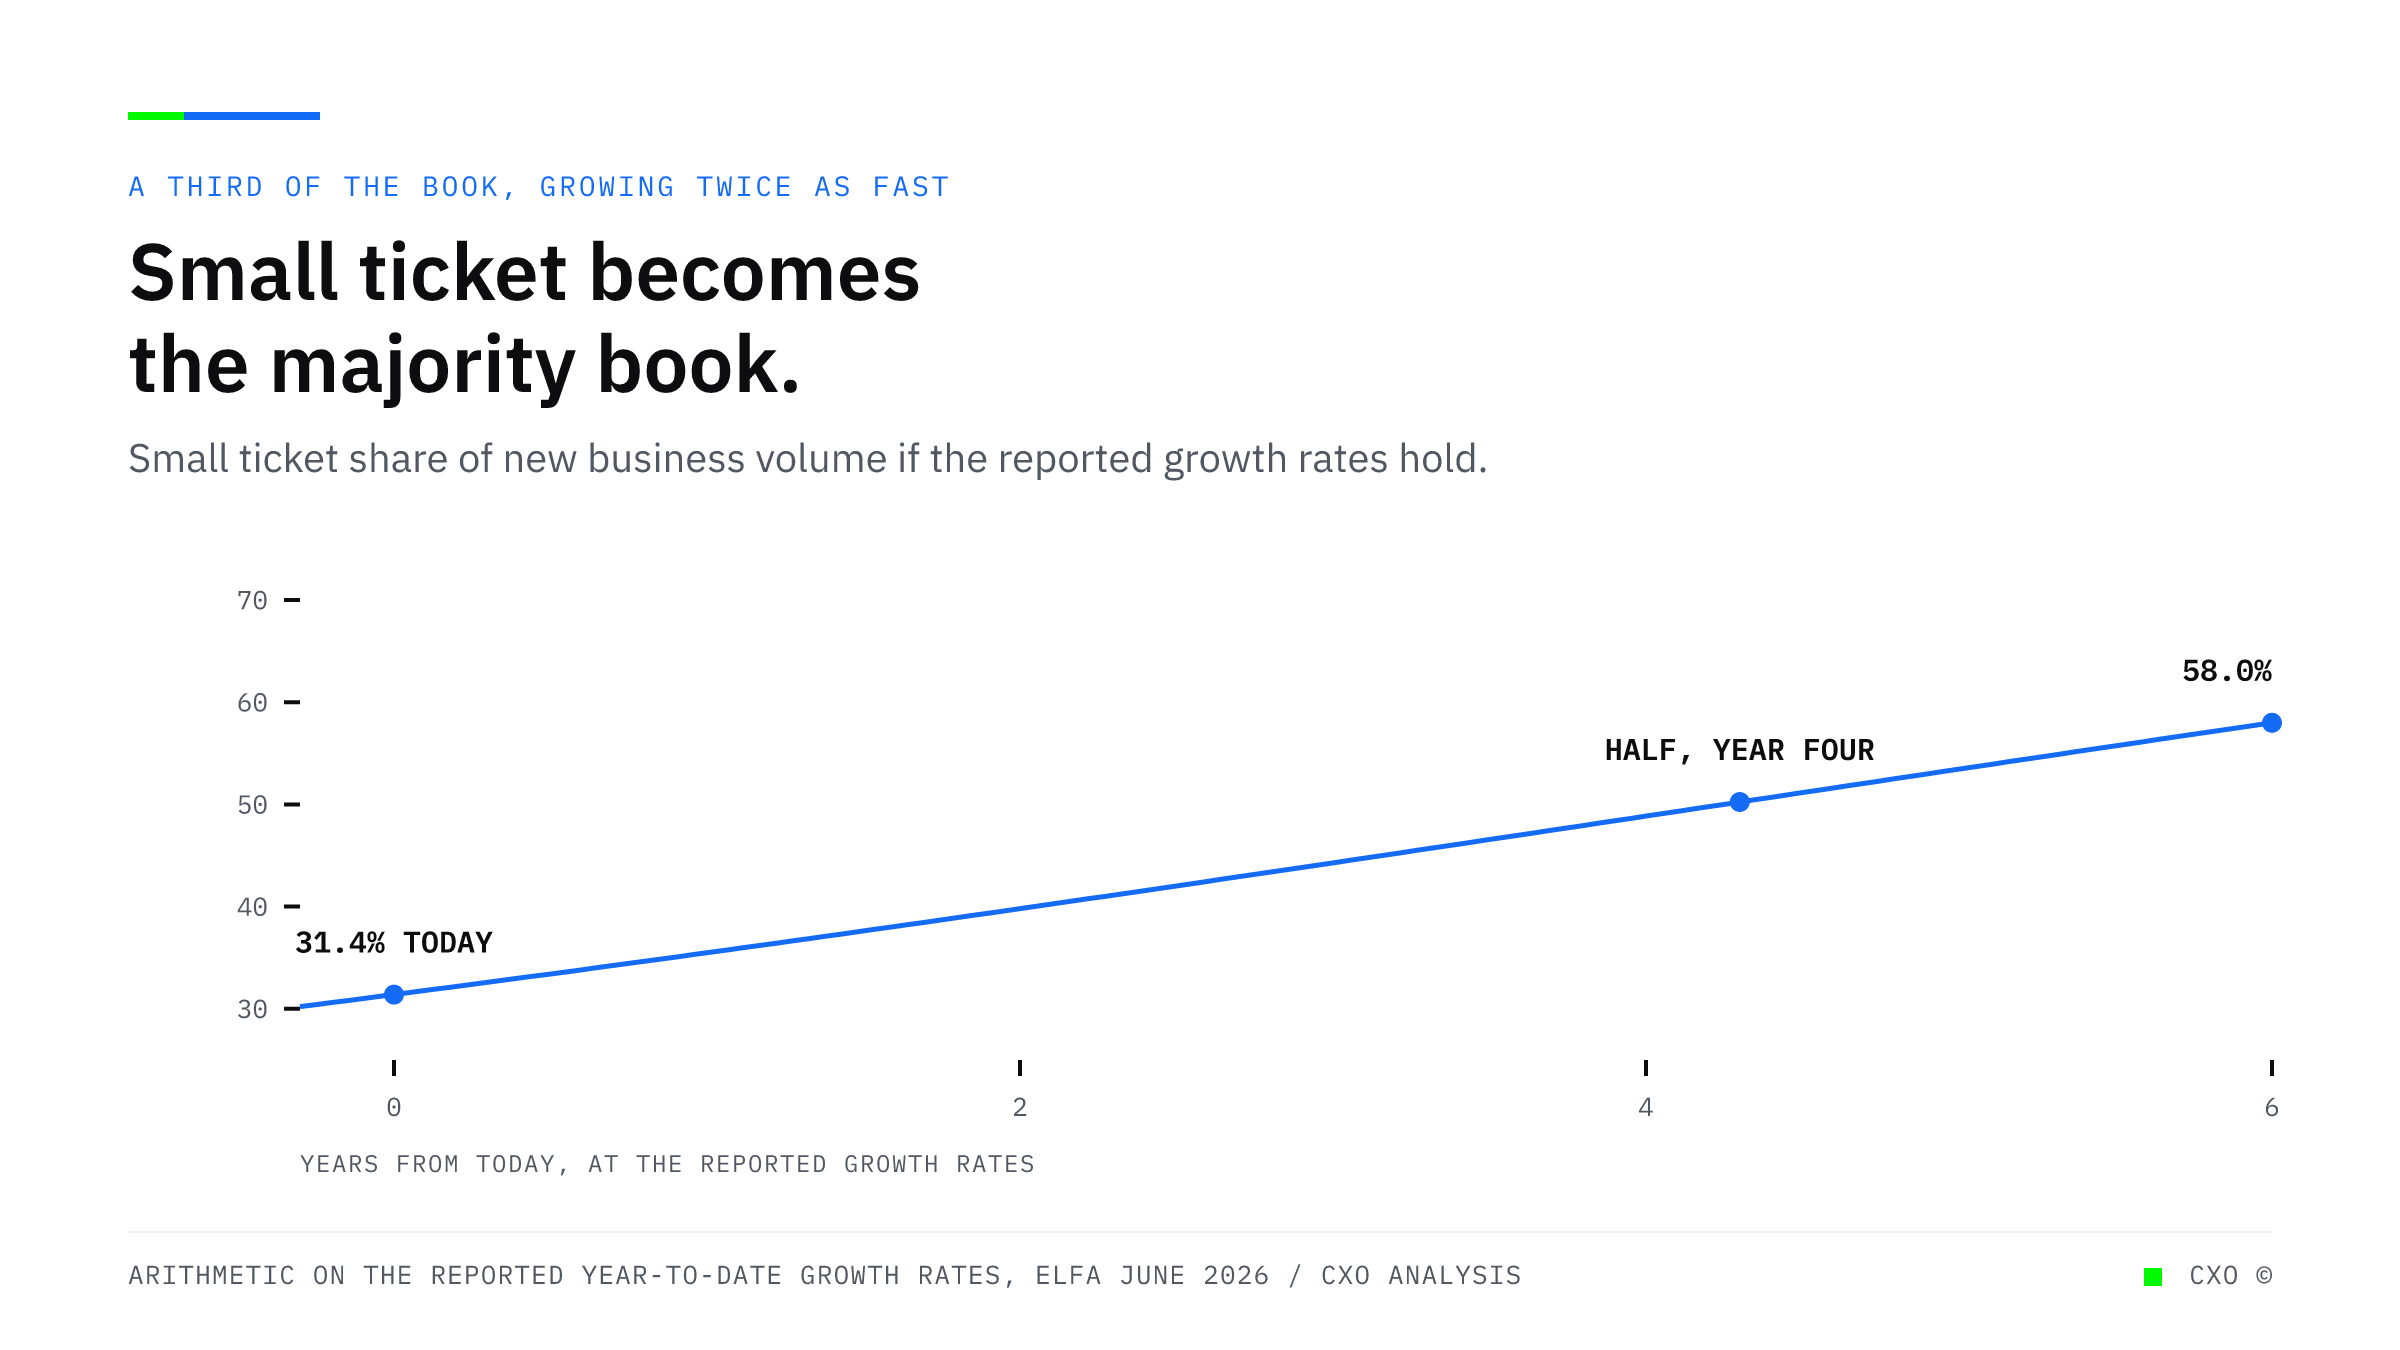
A rising curve showing the small ticket share of new business volume, starting at 31.4 percent today and reaching 50 percent in about four years and 58 percent in six, holding the reported year-to-date growth rates of 25.8 percent for small ticket and 11.3 percent overall.

Equipment Finance Is Growing Fastest in the Segment Where Margin Is Set by Cost Per Deal

Small ticket new business volume is up 25.8 percent year to date against 11.3 percent for the industry overall. The segment growing fastest is the one whose economics are decided by processing cost and cycle time rather than by credit spread.
View Insight
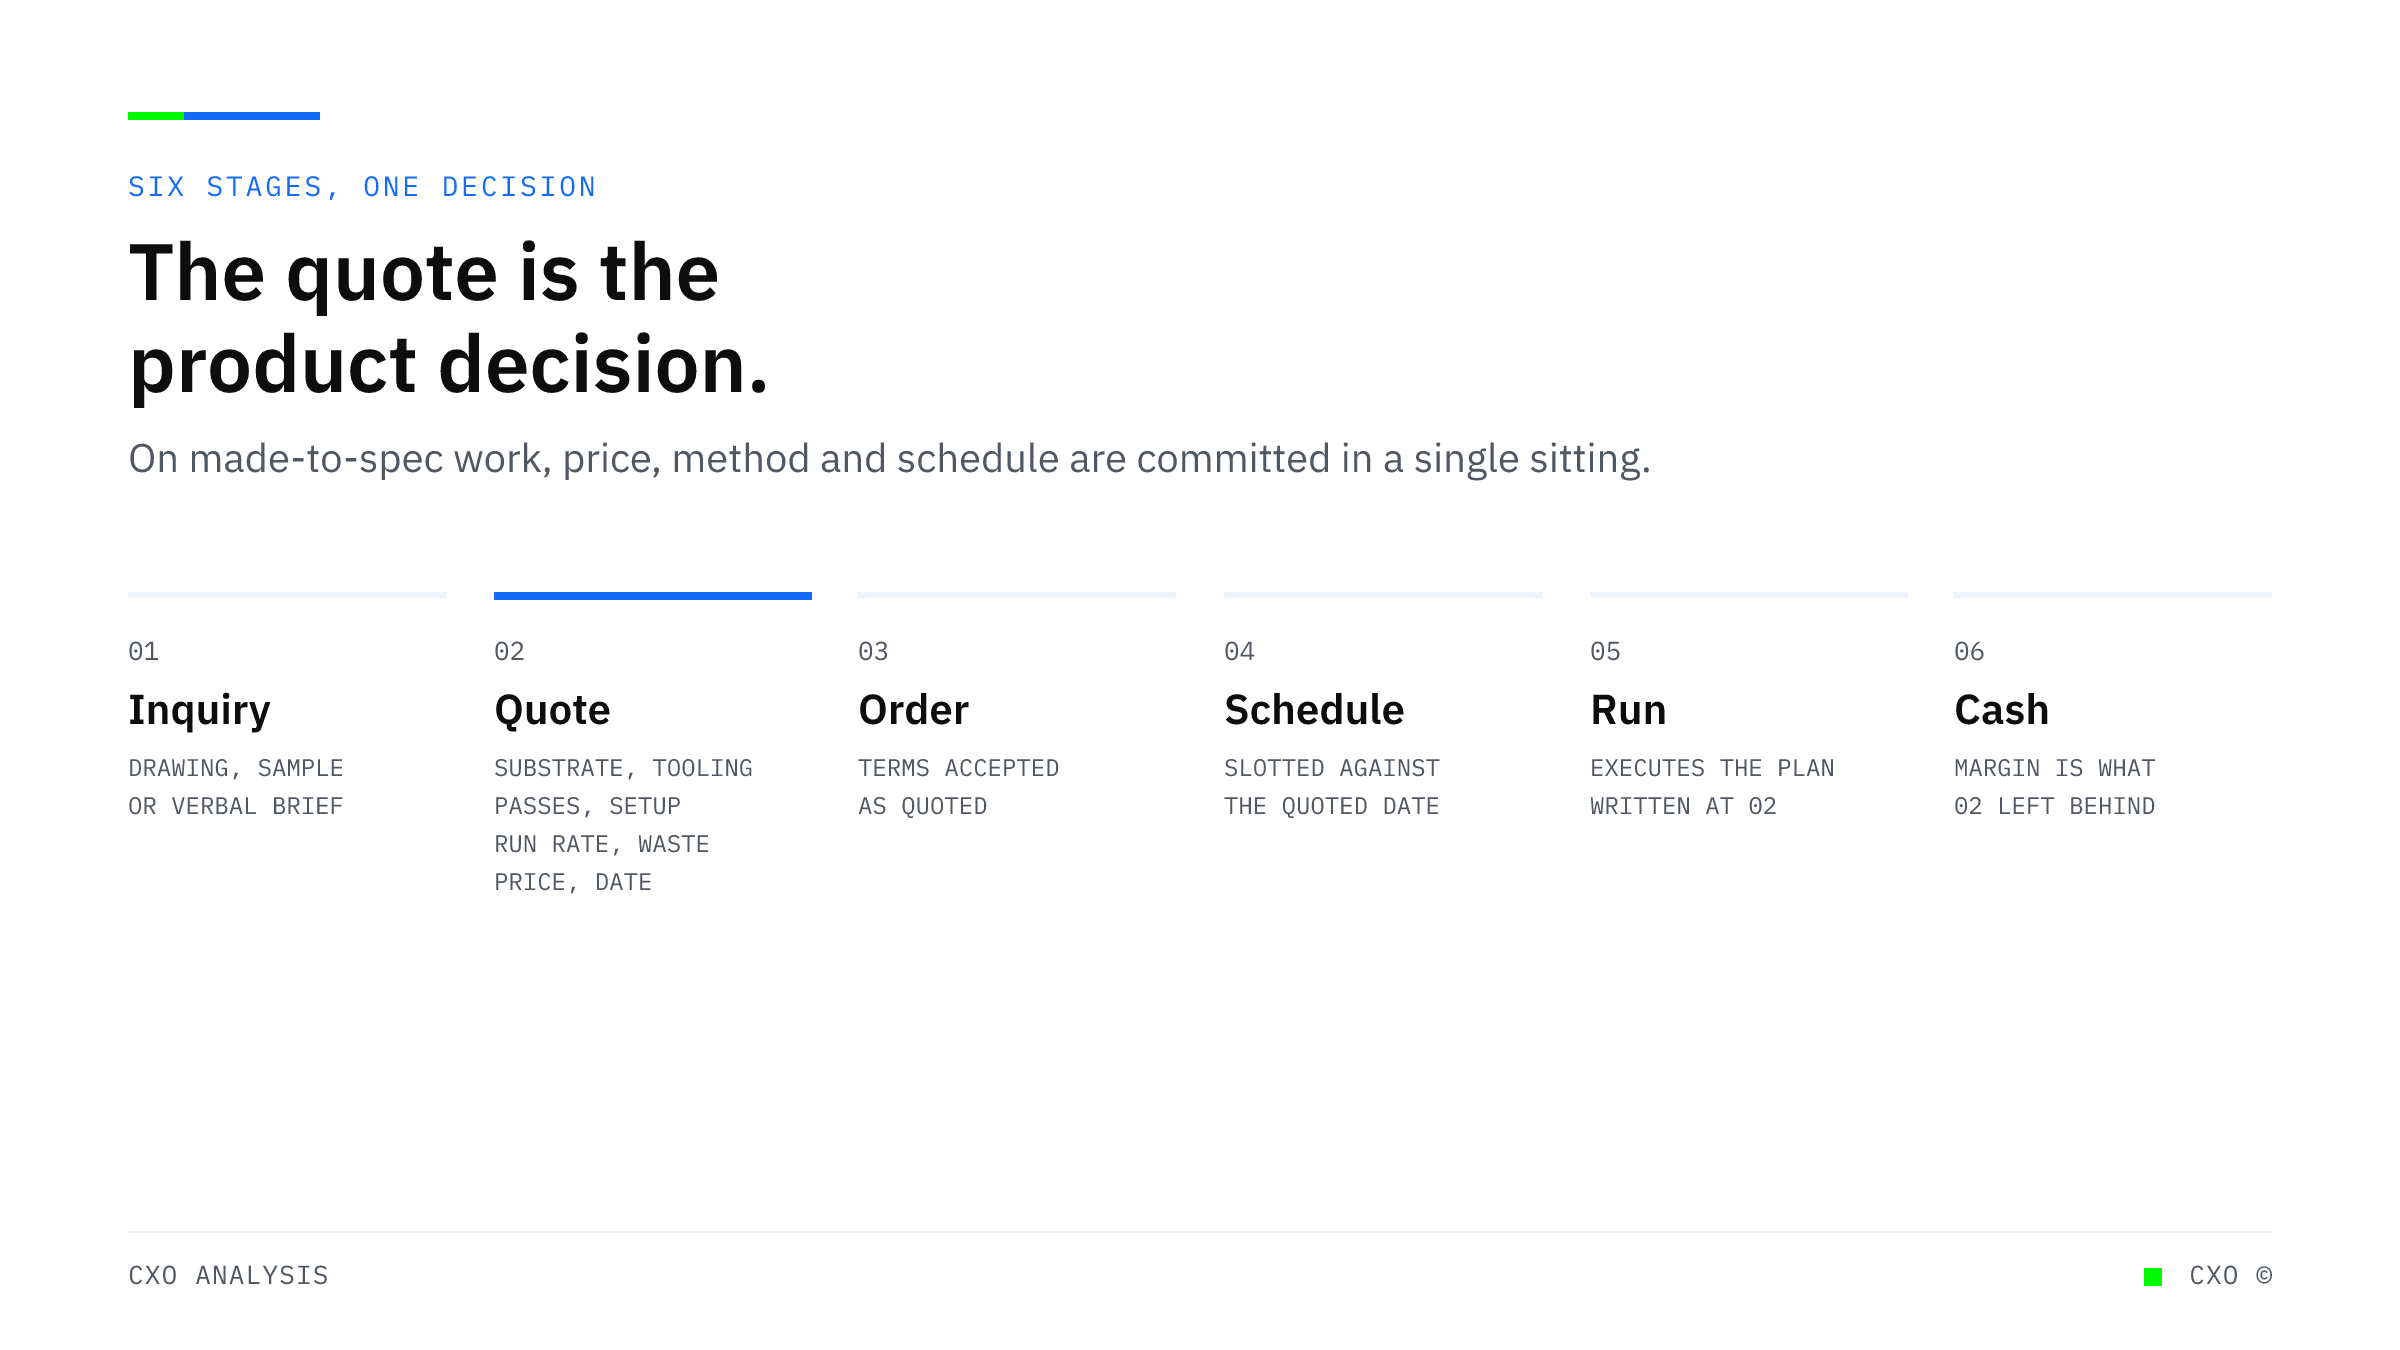
A labeled diagram of six stages from inquiry through cash for made-to-spec production, marking the quote stage as the point where substrate, tooling, run rate, waste allowance, price, and delivery date are all committed at once.

In Made-to-Spec Production, the Quote Is the Only Place the Margin Is Decided

Paper converters hold 51.7 percent of inventory as raw material against 41.5 percent for food manufacturers. That inversion traces back to the front of the process, where the specification, the price, and the schedule are all set at once.
View Insight
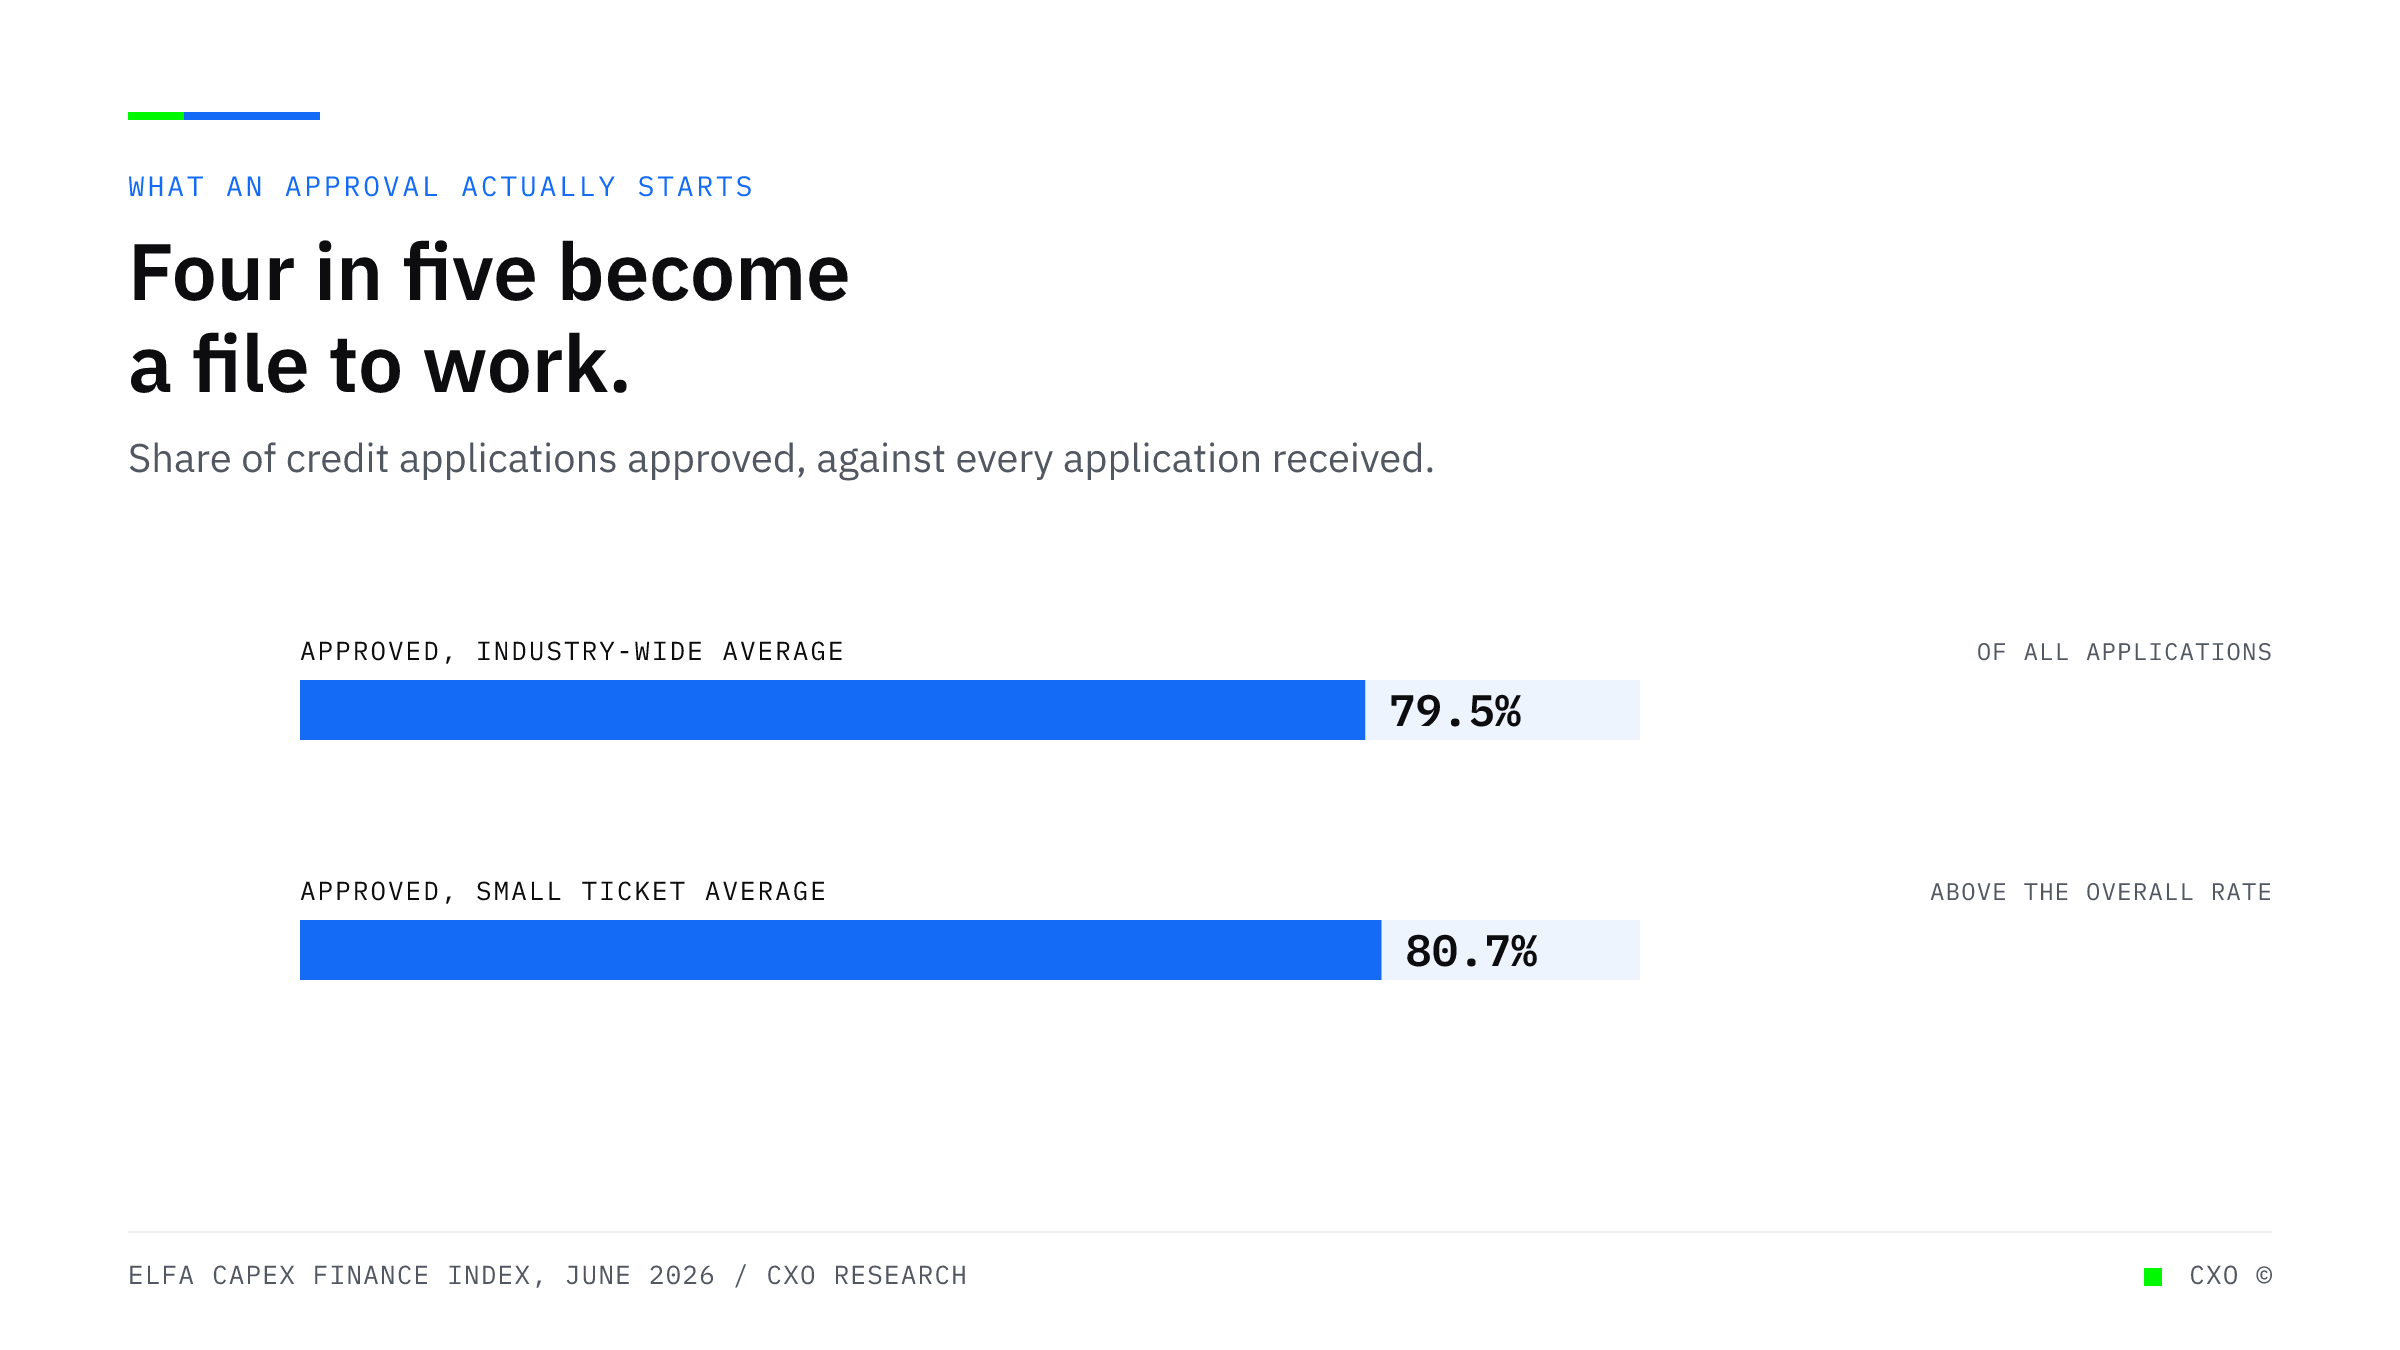
Bullet bars showing an overall credit approval rate of 79.5 percent and a small ticket approval rate of 80.7 percent, each against the full population of applications received.

Approval Rates Near 80 Percent Mean Four in Five Applications Become Work. Volume Is at a Record.

Equipment finance approval rates reached 79.5 percent in June, and 80.7 percent on small ticket. With 2026 volume forecast at the highest level since the survey began in 2006, the constraint is cost per file, not credit appetite.
View Insight
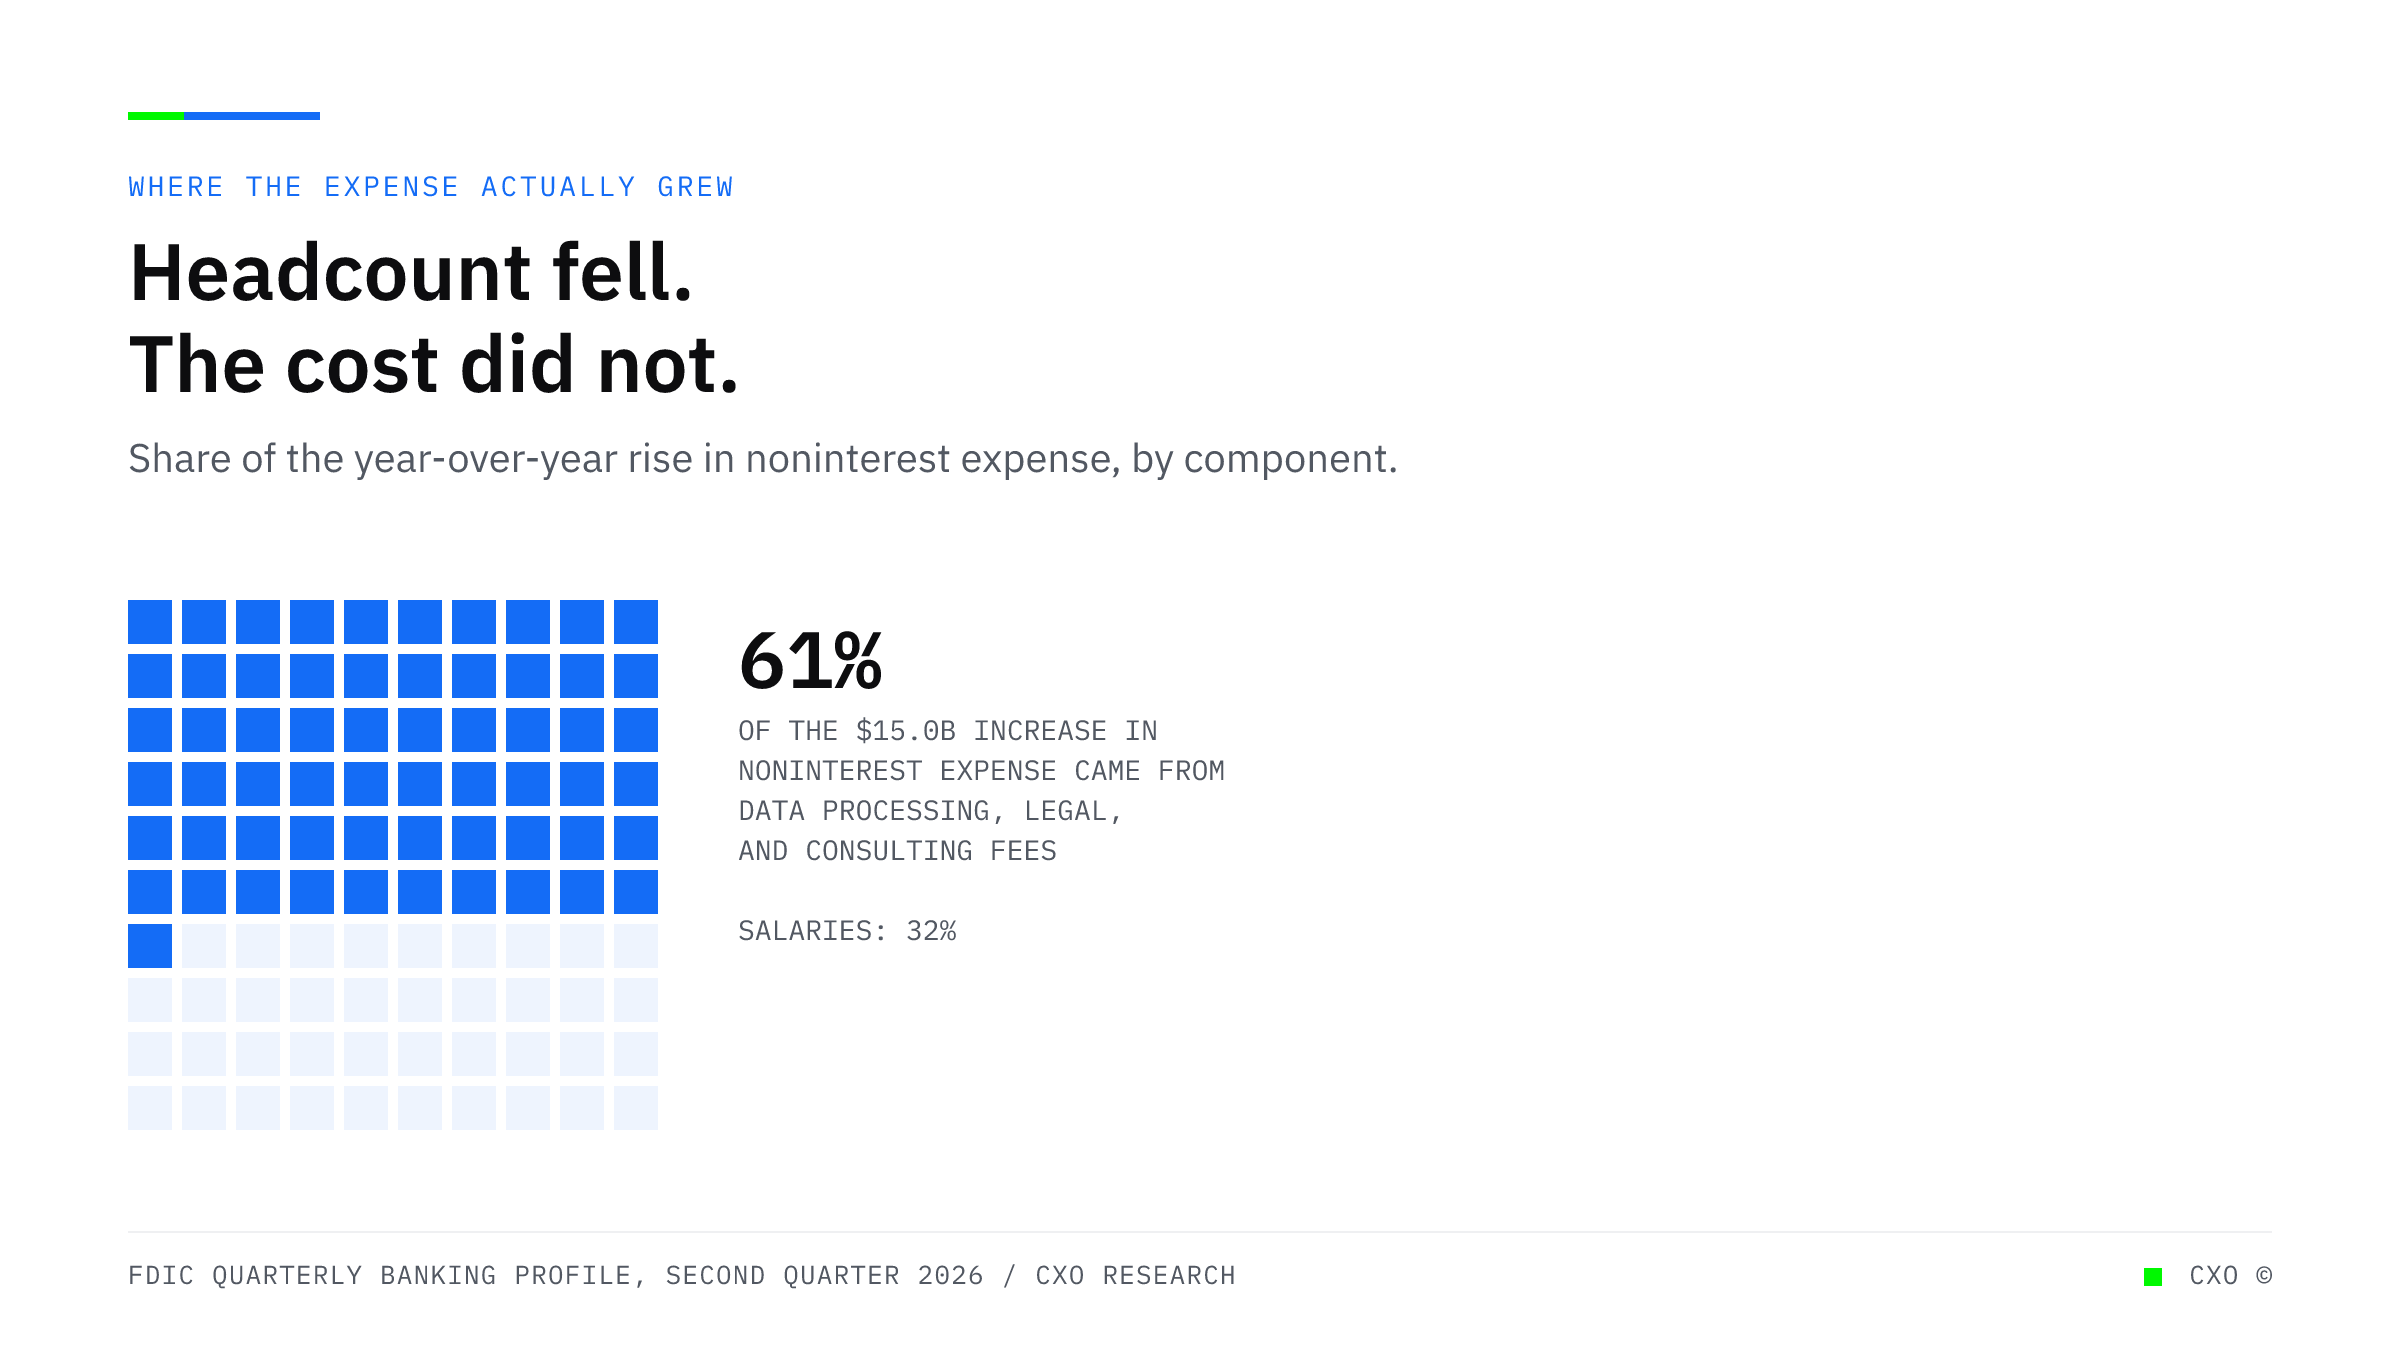
A waffle grid of 100 squares with 10 marked, showing that noninterest expense at insured institutions rose 10 percent year over year while full-time equivalent headcount fell 1.3 percent.

Banks Cut Headcount and Noninterest Expense Rose 10 Percent. The Cost Base Is Not People.

Insured institutions shed 27,662 full-time equivalents over a year while noninterest expense grew 10 percent. When cost rises as headcount falls, the expense is attached to the work rather than to the workforce.
View Insight
Grouped bar chart showing faster-moving financial firms lead incumbents 47% to 30% in advanced AI adoption and 19% to 6% at the fully transforming stage.

Everyone in Finance Adopted AI. Almost No One Rebuilt the Operation.

Process automation runs at 79% of financial firms, but only 14% call AI transformational. For alternative lenders, the gap between adopting tools and rebuilding the operation is the next competitive edge.
View Insight
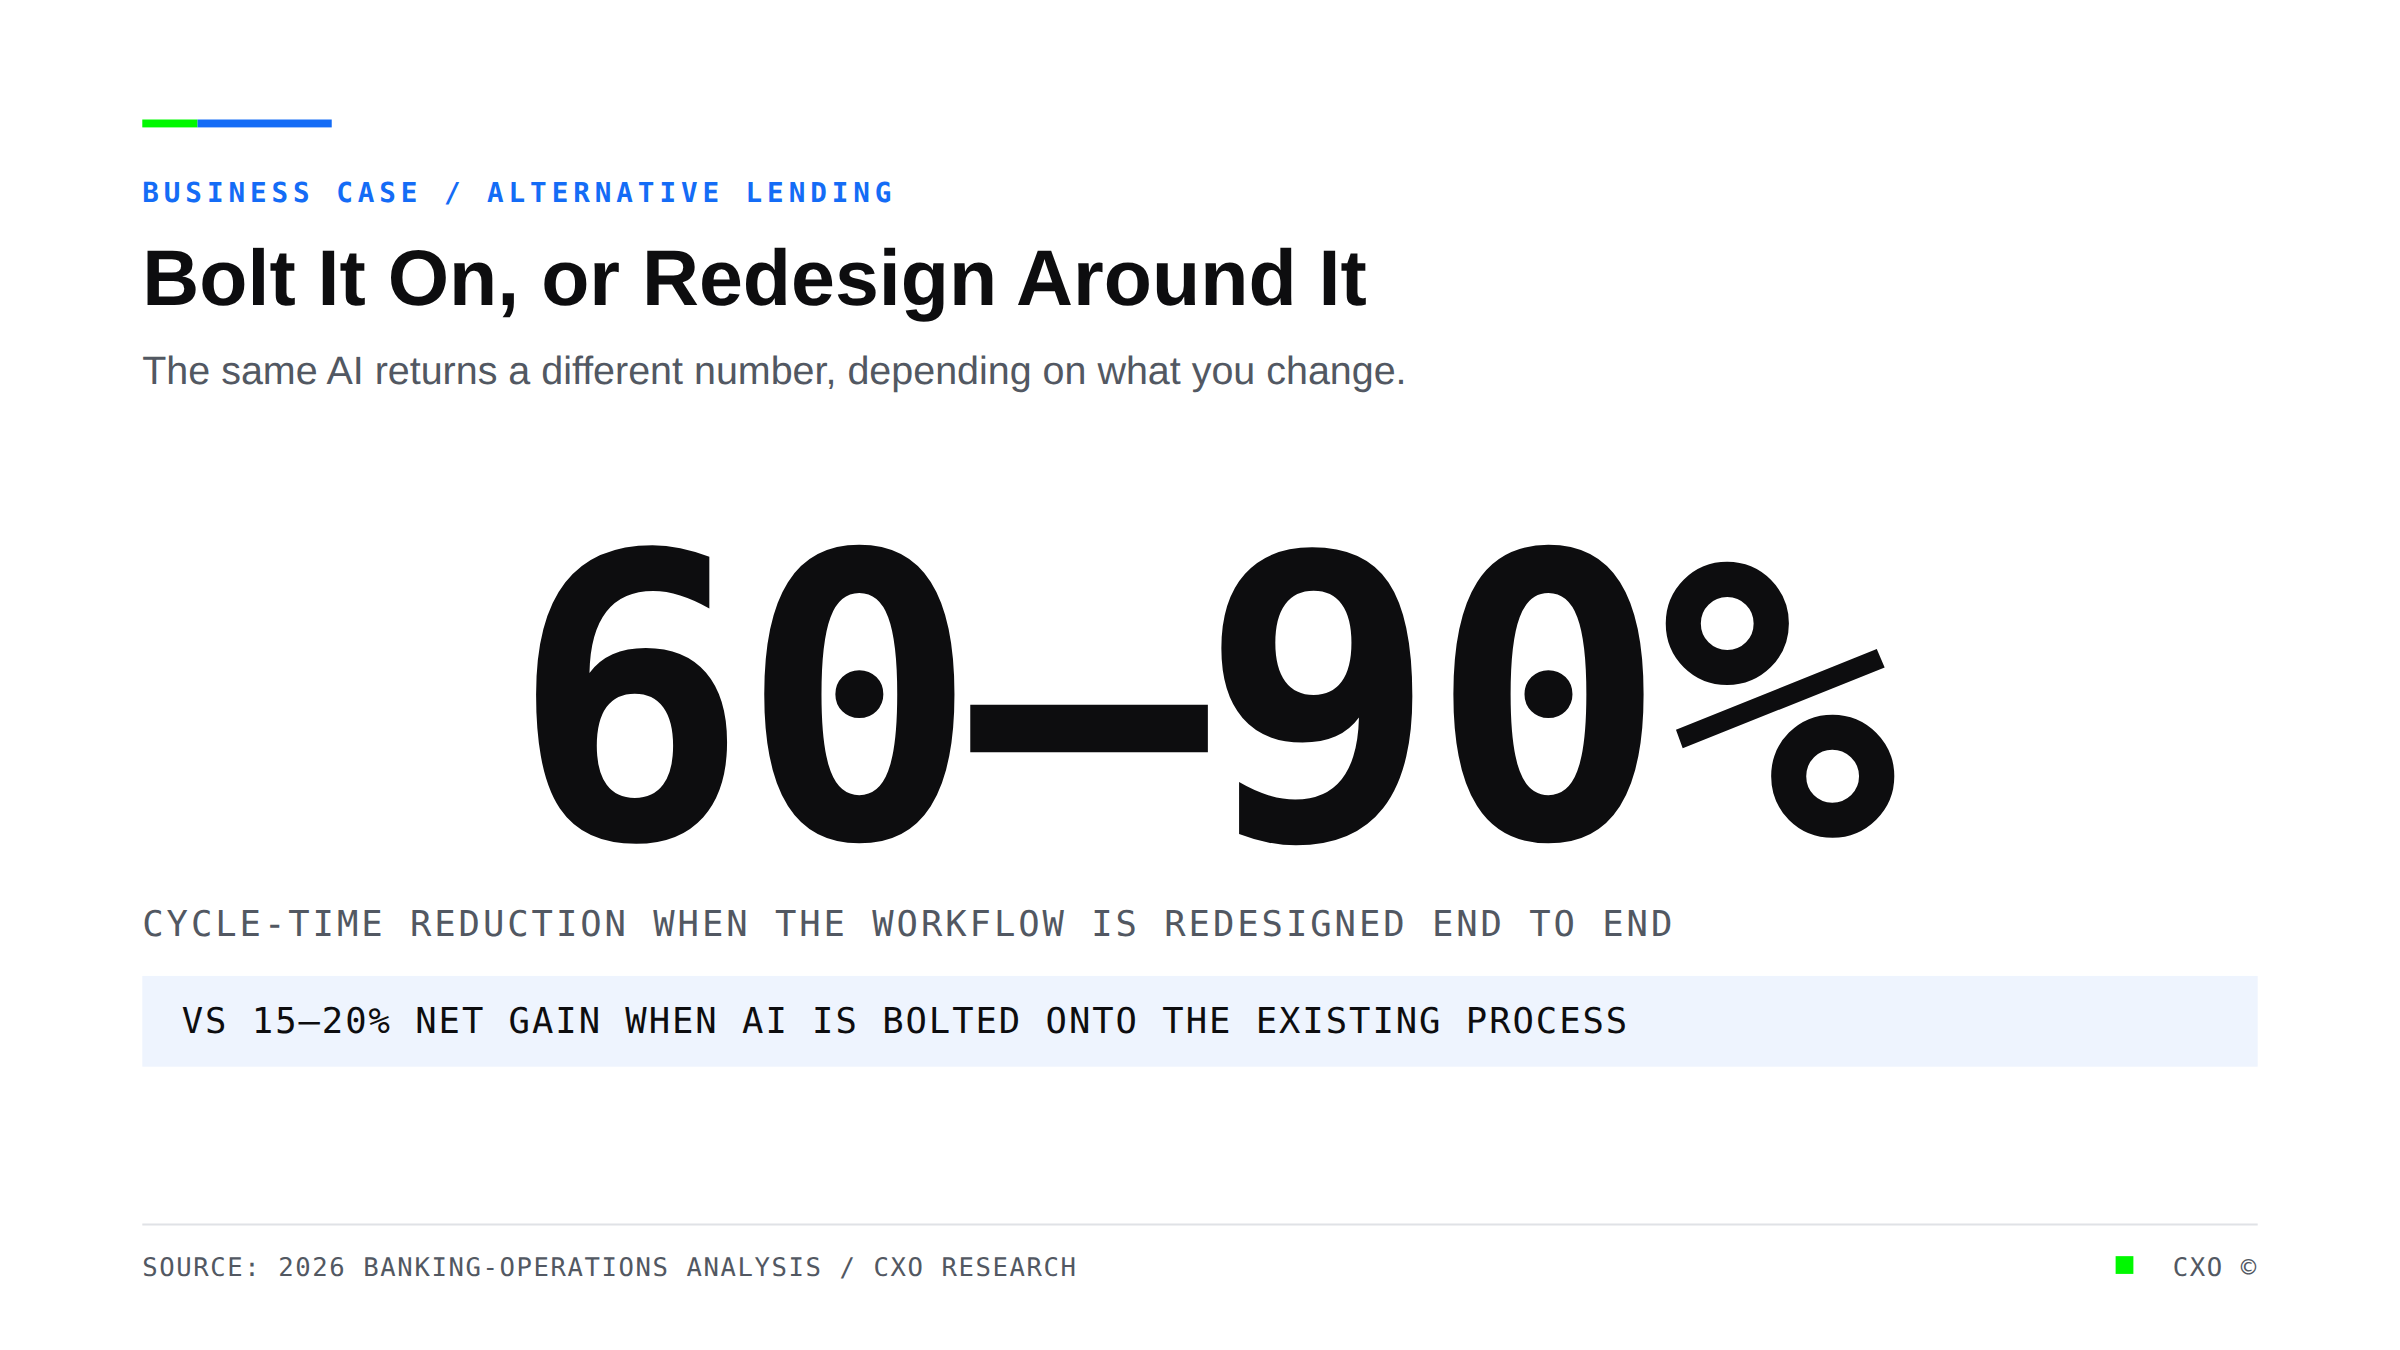
Statement graphic showing a 60 to 90 percent cycle-time reduction when a lending workflow is redesigned end to end, versus a 15 to 20 percent net gain when AI is bolted onto the existing process.

Bolt It On, or Redesign Around It: Why Your 2025 AI Purchase Underdelivered

Most lenders blame the technology when their AI underdelivers. The real issue is a point tool bolted onto an unchanged process. See why end-to-end redesign drives 60 to 90 percent cycle-time reductions.
View Insight
Bar chart showing the gap between companies experimenting with AI agents and companies that have scaled agentic AI to measurable operational value

Only 10% of Companies Using AI Are Actually Changing Their Cost Structure

Nearly two-thirds of companies have tried AI agents. Fewer than 10% restructured their operations. Here's what the 10% actually did differently.
View Insight
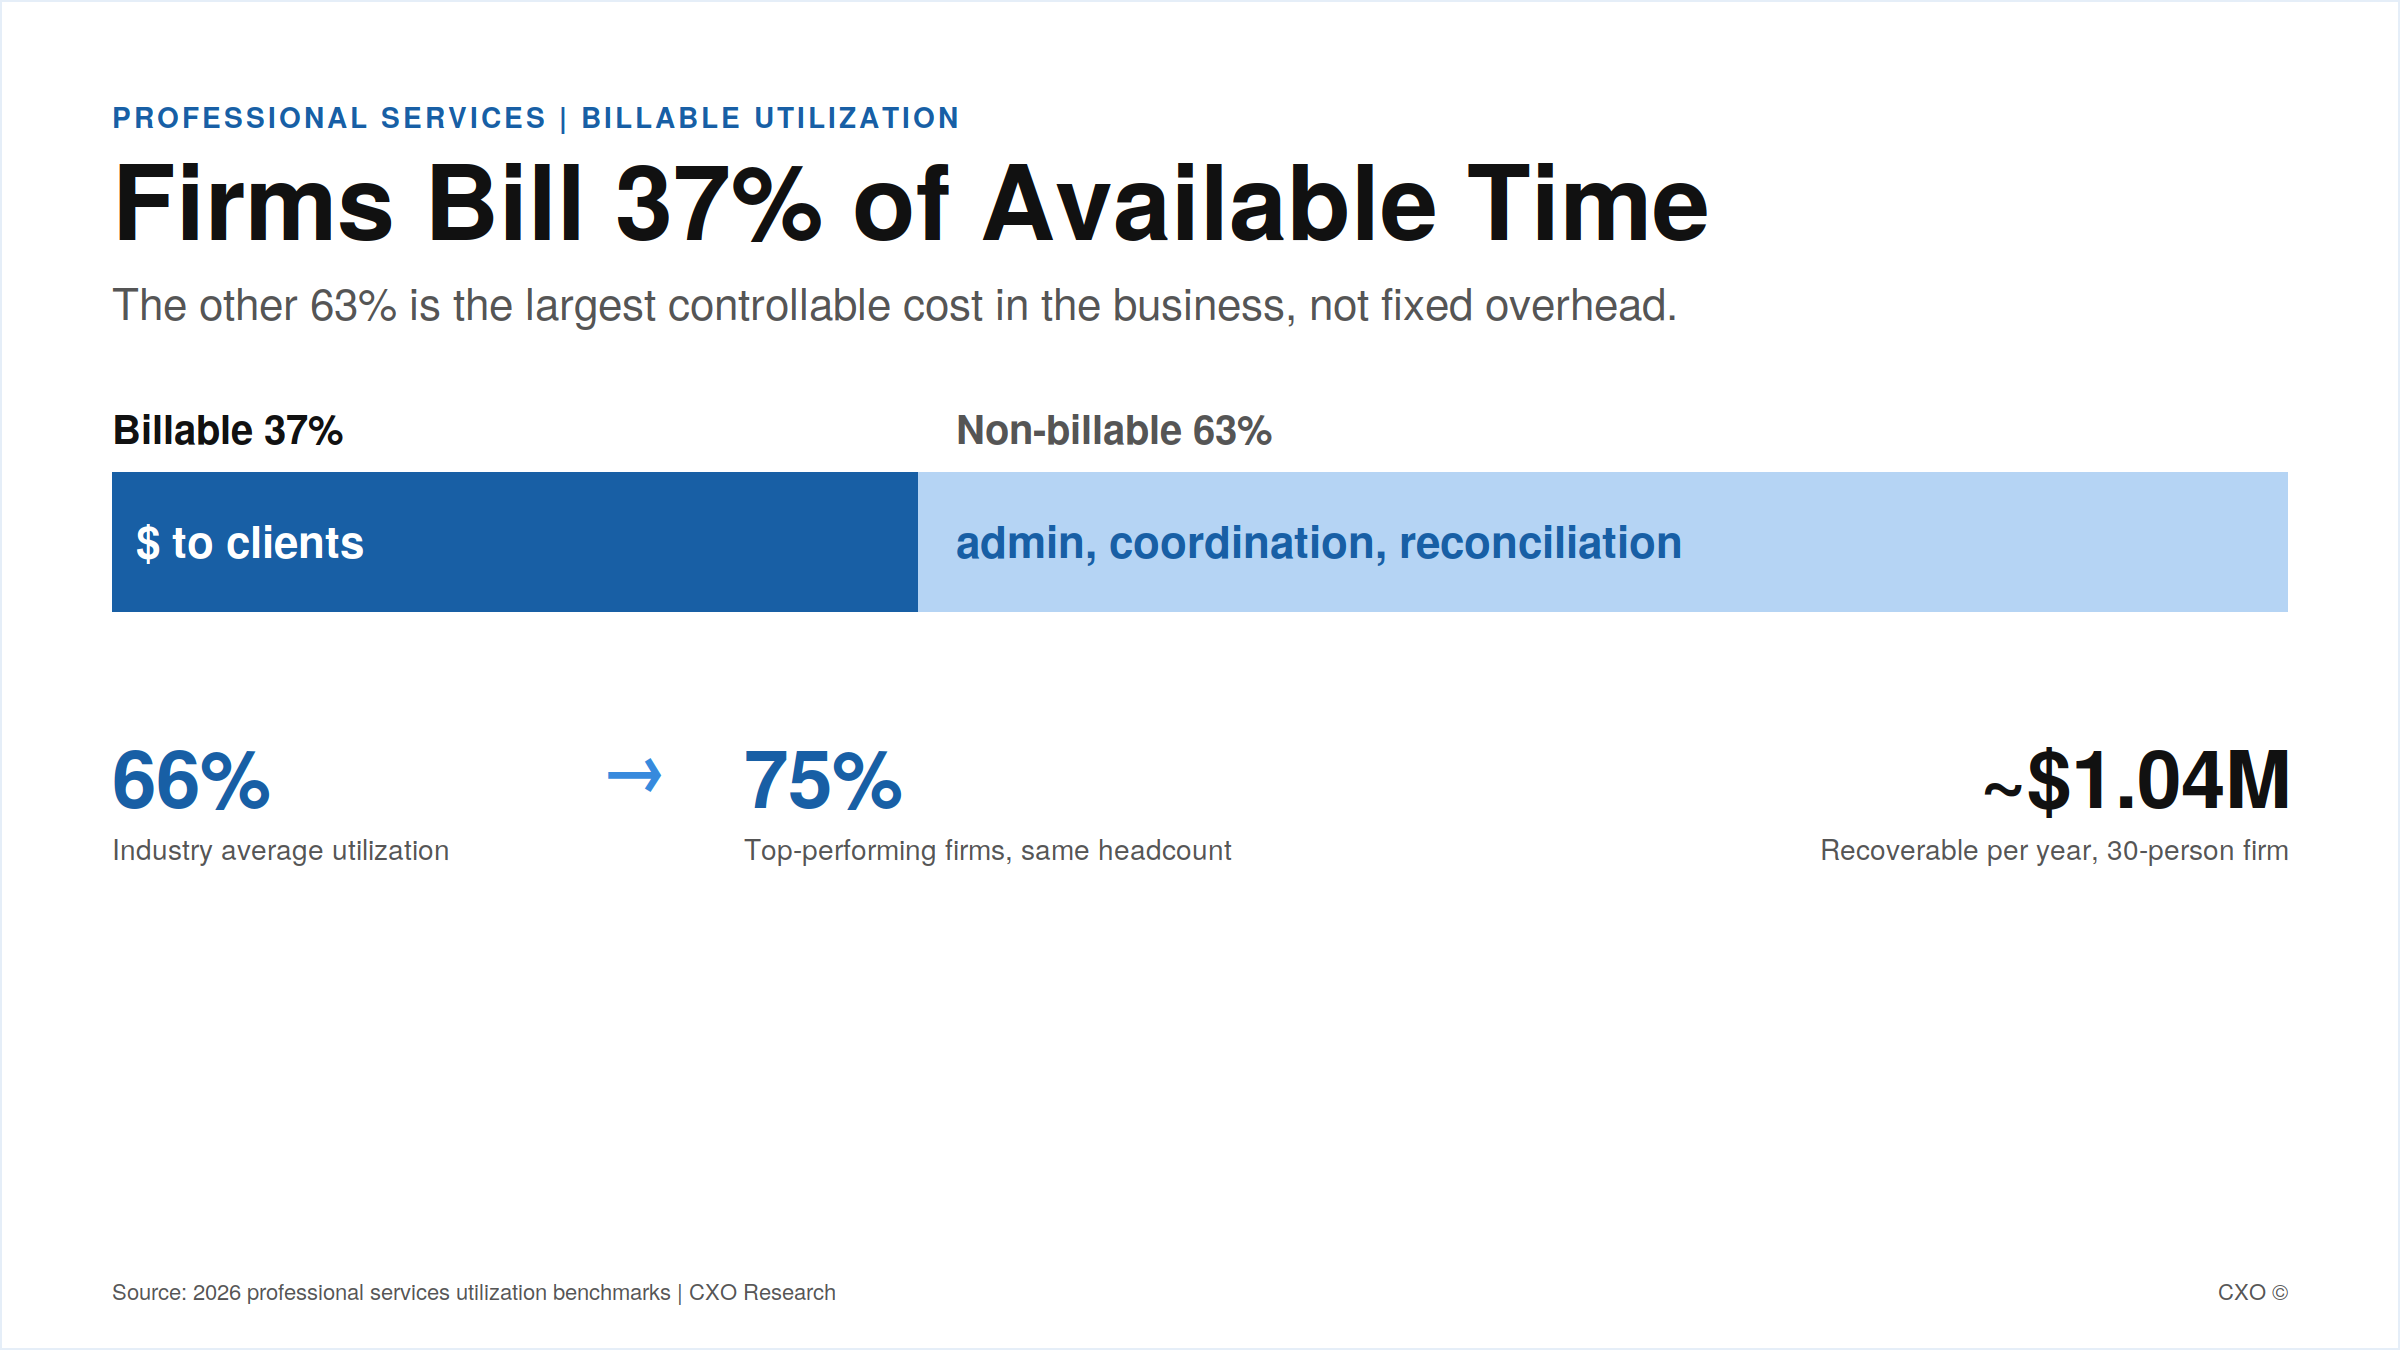
Split bar showing 37 percent of professional services time is billable and 63 percent non-billable, with utilization rising from 66 percent to 75 percent and roughly $1.04M recoverable at a 30-person firm

Your Partners Bill 37% of Their Day. The Other 63% Is Where Your Margin Is Hiding.

Professional services firms bill about 37% of available time while roughly 14 non-billable hours a week per person quietly erode margin. Here is where the money hides and how to reclaim it without hiring.
View Insight
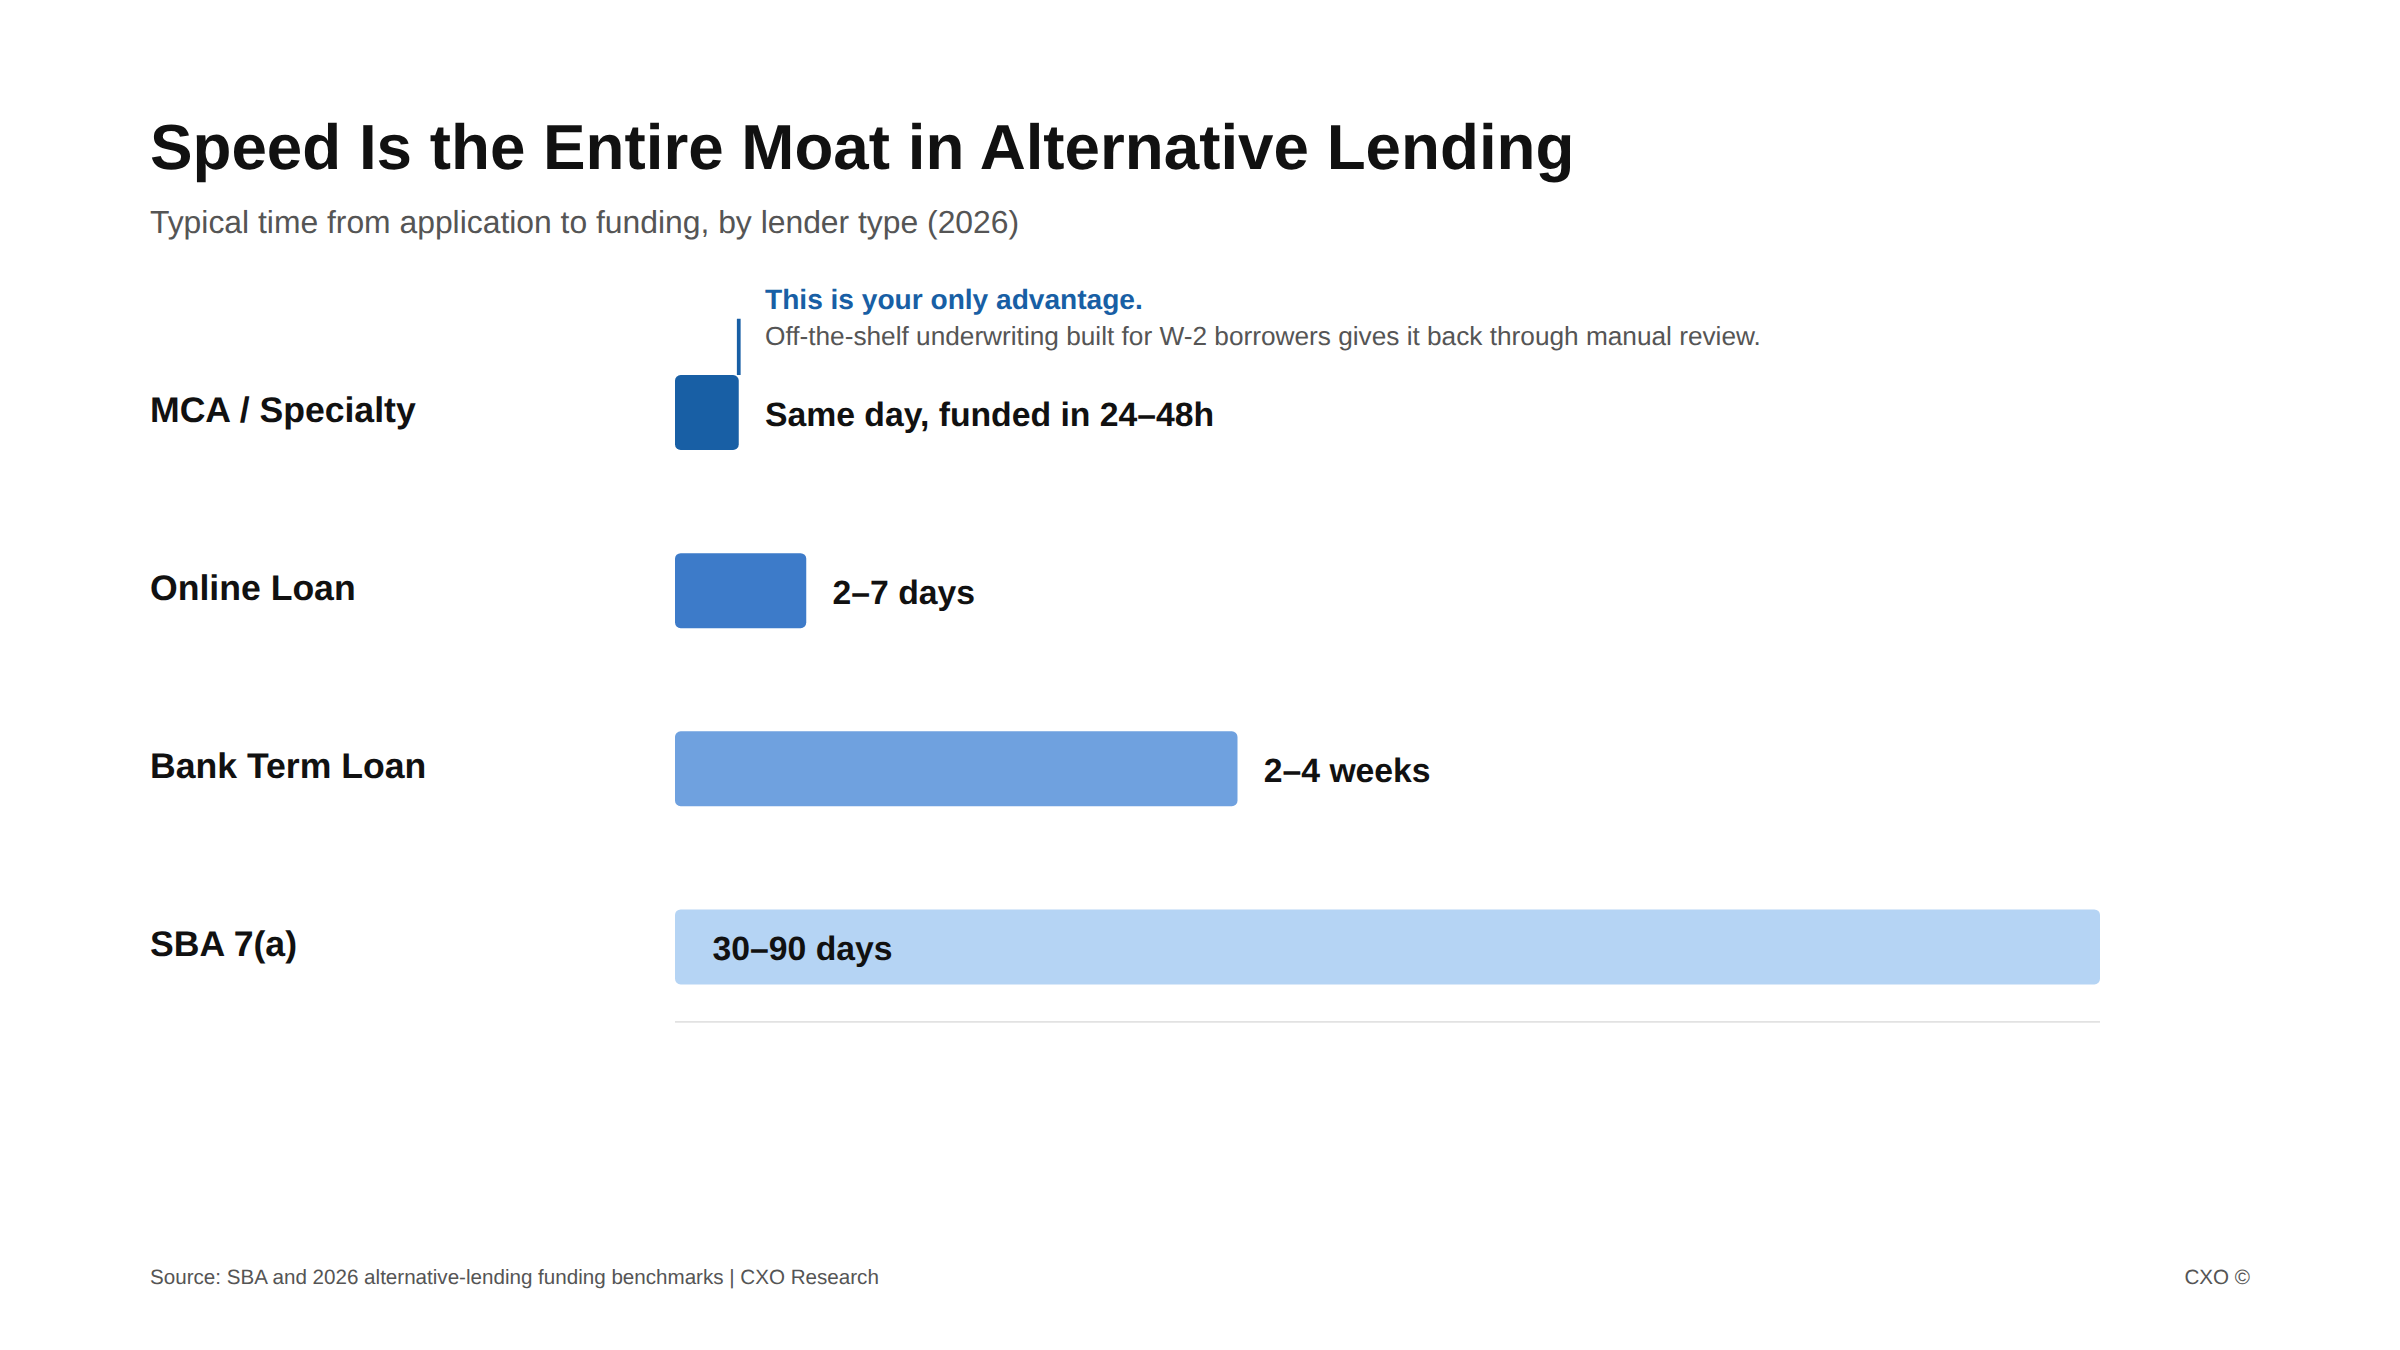
Horizontal bar chart comparing time to funding by lender type, showing MCA same-day funding against bank and SBA timelines of weeks to months

Off-the-Shelf Underwriting Was Built for W-2 Borrowers. You Don't Lend to Them.

Off-the-shelf underwriting was built for W-2 borrowers, not the cash-flow businesses alternative lenders fund. Here is where it leaks deals and how to fix it.
View Insight

Start with the process that costs you most.

A conversation first. A structured assessment when it earns one. Or see what a discovery finds before you book anything.

Book a discovery call See what a discovery finds